GLOBAL ECONOMY
The United States (US) economy showed remarkable resilience as the S&P Global US Composite Purchasing Managers’ Index (PMI) surged to 58.40 in September, its highest level since July 2021, driven by robust services (58.70) and manufacturing (57.00) activity, while unemployment claims fell to 197,000, underscoring continued labor market strength. However, rising inflationary pressures pushed the 10-Year US Treasury Yield above 5.15%, near its highest level since 2007, as markets priced a 67% to 70% probability of another Federal Reserve (Fed) rate hike in October. Meanwhile, the US current account deficit widened to $246billion in the second quarter, equivalent to 3% of Gross Domestic Product (GDP), while crude oil inventories increased by nearly 3 million barrels to 426.40 million barrels.
The United Kingdom (UK) Pound Sterling hovered near a three-month low around £1/$1.33, pressured by expectations of further Federal Reserve (Fed) tightening and concerns over domestic public finances. UK public sector borrowing rose to £18.30billion in August, exceeding both £15.70billion market expectations and last year’s £15.40billion, while public debt remained elevated at 93.80% of Gross Domestic Product (GDP). The S&P Global UK Composite Purchasing Managers’ Index (PMI) eased to 51.70 from 52.50, although manufacturing was resilient, rising to 52.00 supported by artificial intelligence and defence-related spending. Markets are pricing an 80.00% probability of a Bank of England (BoE) rate hike in November, with policymakers warning that elevated energy prices could keep inflation under pressure.
The Euro weakened to around €1/$1.14, its lowest level in nearly two months, as political uncertainty in Germany, mounting concerns over France’s public finances and expectations of further Federal Reserve (Fed) rate hikes boosted demand for the US dollar. Germany’s ruling Christian Democratic Union (CDU) suffered major regional election setbacks, while ratings agencies raised fresh concerns about France’s fiscal outlook ahead of the 2027 presidential election. While the S&P Global Eurozone Manufacturing Purchasing Managers’ Index (PMI) held at 52.70, supported by stronger export orders and manufacturing output reaching a 55-month high of 53.40. Meanwhile, bank lending to households grew 3.10% year-on-year to €7.26trillion, while business lending slowed to 4.20%.
The offshore Yuan weakened to ¥6.72/$1, pressured by a stronger dollar and market expectations of a 67.00% probability of a Federal Reserve rate hike in October. The People’s Bank of China (PBOC) maintained its benchmark lending rates at record lows for a 16th consecutive month, keeping the one-year Loan Prime Rate (LPR) at 3.00% and the five-year LPR at 3.50%, reflecting policymakers’ caution amid Middle East tensions and slowing domestic demand. While industrial production accelerated and exports remained resilient due to strong artificial intelligence-related demand, retail sales growth weakened, credit demand from households and businesses remained subdued.
Next Week, global markets will focus on key economic data, central bank decisions and geopolitical developments amid persistent inflation and energy-price pressures.
GLOBAL MARKETS
US equities ended the week mixed as investors balanced strong economic growth and sustained optimism around artificial intelligence with rising Treasury yields, elevated inflation and expectations of further Federal Reserve (Fed) tightening. Market sentiment remained volatile after stronger-than-expected business activity data pushed bond yields to multi-decade highs. Compared to last week, the Dow Jones, S&P 500, and Nasdaq increased by 0.28%, 1.21% and 2.06% to close at 51,828.62, 7,743.41 and 27,068.72 respectively.
European equities closed higher during the week, supported by resilient Eurozone economic activity, although gains were tempered by persistent inflation concerns, rising bond yields and expectations of further European Central Bank (ECB) tightening. Compared to last week, the German DAX, CAC 40 and the FTSE 100 increased by 0.41%, 0.16% and 0.34% to close at 25,408.64, 8,077.80 and 10,695.25 respectively.
Asian equities ended the week mixed as rising global bond yields and expectations of further monetary tightening weighed on sentiment, while China’s steady interest-rate stance and resilience in technology stocks provided some support. Compared to last week, the Hang Seng Index decreased by 0.97% to close at 24,510.09, while the TOPIX Index increased by 0.92% to close at 4,128.59.
Next Week, global markets are expected to focus on US economic data, China’s policy signals and developments from the US-China summit, while Treasury yields, the US dollar and energy prices remain key drivers of market sentiment and monetary policy expectations.
DOMESTIC ECONOMY
CBN Slashes Benchmark Rate to 23% in Biggest Cut Since 2006 as Inflation Falls to 15.39%; Equities Poised for Further Gains
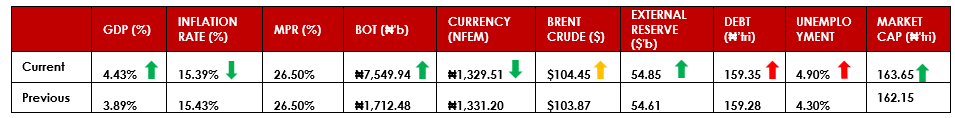
The Central Bank of Nigeria (CBN) reduced the Monetary Policy Rate (MPR) by 350 basis points to 23% from 26.50%, marking its second-rate reduction in 2026 and the largest cut since 2006. The Monetary Policy Committee (MPC) described the move as an operational “reset” aimed at improving monetary policy transmission amid easing inflation, which declined for a third consecutive month to 15.39% in August 2026, while real Gross Domestic Product (GDP) growth accelerated to 4.43% in the second quarter and the Purchasing Managers’ Index (PMI) remained expansionary at 52.70%. The MPC retained the Cash Reserve Requirement (CRR) at 45% for commercial banks, 16% for merchant banks and 75% for non-Treasury Single Account (TSA) public sector deposits, while resetting the corridor to place the Standing Lending Facility (SLF) at 23.50% and the standing facilities corridor at +50/-300 basis points around the 23.00% MPR, implying an SLF rate of 23.50% and an SDF rate of 20%. Analysts expect lower fixed-income yields, with the 364-day Treasury bill rate already down to 15.89% from 16.62%, to accelerate portfolio rotation into equities.
Cash Outside Banks Rebounds to ₦4.87Trillion Despite CBN’s Digitalization Push, Money Supply Hits ₦139.38Trillion
Cash held outside Nigeria’s banking system rose by ₦70.90billion or 1.48% month-on-month to ₦4.87trillion in August 2026, reversing a three-month decline that had reduced out-of-bank cash holdings by ₦391.80billion between May and July. Despite the rebound, currency outside banks remains ₦381.30billion below the ₦5.25trillion recorded in January 2026, although it is ₦419billion or 9.40% higher than the ₦4.45trillion reported in August 2025. The increase comes as the Central Bank of Nigeria (CBN) pushes to deepen digital payments, targeting 95% financial inclusion by 2028 and aiming to reduce cash held outside banks to below 40% of total currency in circulation. Meanwhile, Nigeria’s broad money supply (M3) expanded to ₦139.38trillion in August 2026, up 16.40% year-on-year from ₦119.69trillion, while net domestic assets rose to ₦101.99trillion from ₦101.07trillion in July. The figures highlight continued liquidity growth in the economy, even as the apex bank intensifies efforts to transition Nigeria toward a more inclusive, technology-driven and cash-light financial system.
Government Credit Falls ₦7.34Trillion in Three Months as Private Sector Borrowing Climbs to ₦84.55Trillion
Credit to Nigeria’s government declined for the third consecutive month, falling to ₦32.70trillion in August 2026 from ₦33.92trillion in July and ₦40.03trillion in June, representing a cumulative decline of ₦7.34trillion over the three-month period. In contrast, private sector credit rose for a third straight month to ₦84.55trillion, up 1.35% month-on-month from ₦83.43trillion, signaling a gradual shift in lending toward businesses and households. Despite the recent improvement, private sector credit remains below the ₦94.61trillion peak recorded in February 2026. Economists believe the decline in government credit could ease the crowding-out effect, where banks favor high-yield, lower-risk government securities over lending to the productive sector. Nigeria’s net domestic credit also edged lower to ₦117.25trillion in August from ₦123.29trillion in June, while other assets (net) declined to ₦9.14trillion from ₦9.93trillion in July. Although the Central Bank of Nigeria (CBN) did not specify the reasons behind the drop in government credit, analysts view the trend as potentially positive for economic growth if it creates more room for private-sector lending, investment, and business expansion amid the recent interest-rate reset that lowered the Monetary Policy Rate (MPR) to 23%.
Next Week, attention will focus on how quickly the Monetary Policy Rate cut translates into lower market yields and borrowing costs, while investors monitor inflation, liquidity and exchange-rate stability for signs the easing cycle can be sustained.
EUROBOND MARKET
Nigerian sovereign Eurobonds traded weaker during the week as investor sentiment remained cautious amid rising United States (US) Treasury yields, higher-for-longer Federal Reserve (Fed) rate expectations and tighter global financial conditions. As a result, demand for Nigeria’s dollar-denominated debt moderated, pushing the average sovereign Eurobond yield up by 20bps W-o-W to 7.27%.
Next week, Nigeria’s Eurobond market is expected to remain cautious, with performance likely to be driven by movements in US Treasury yields, Federal Reserve (Fed) policy expectations, oil prices and broader emerging-market risk sentiment, which could keep yields elevated in the near term.
ALTERNATIVE ASSETS
GOLD
Gold ended the week under pressure, trading around $4,285.00/oz, as elevated Treasury yields and growing expectations of further Federal Reserve (Fed) rate hikes outweighed support from geopolitical uncertainty. Markets are pricing a nearly 70% probability of a Fed rate hike in October, which continued to strengthen the US dollar and weigh on bullion.
OIL
Brent crude closed around $104.45/bbl, remaining above $100.00/bbl despite Friday’s pullback, as markets balanced prospects of a potential US-Iran agreement and reopening of the Strait of Hormuz against ongoing Middle East supply risks.
ETFs
Investor flows remained tilted toward defensive assets as elevated bond yields, geopolitical uncertainty and expectations of further monetary tightening supported demand for quality fixed-income and safe-haven exposures.
Next week, Gold and Oil will be driven by US economic data, Federal Reserve (Fed) rate expectations, Treasury yields, the US dollar and developments surrounding Middle East energy supply risks.
MONEY MARKET AND FIXED INCOME
System liquidity was volatile during the week, opening at a surplus of ₦3.80trillion an increase of ₦1.05trillion from Friday’s close owing to Coupon Payments, Tuesday and Wednesday saw more inflows from Bond coupon payment, FAAC and OMO maturities taking liquidity to ₦7.45trillion before declining significantly to ₦5.98trillion following ₦1.64trillion decrease from NTB and OMO auction settlements.
The tighter liquidity position was reflected in funding rates, as the minimum, weighted average and maximum Nigerian Overnight Financing Rates (NOFR) were all unchanged at 20%, 20%, and 22.22% respectively. Meanwhile, average secondary-market T-bill yields declined following the outcome of the 23 September 2026 auction, where stop rates cleared at 15.50%, 15.80% and 15.89% across the 91-day, 182-day and 364-day tenors respectively, reflecting strong investor demand and expectations of a lower interest-rate environment.
Next week, money-market liquidity is expected to remain stable, supported by system liquidity and Treasury bill maturities, while the recent Monetary Policy Rate (MPR) cut and the upcoming fourth-quarter Treasury bills auction calendar could shape investor demand and short-term rates.
DOMESTIC MARKETS
CBN Raises ₦8.14Trillion via Treasury Bills, Exceeding Q3 Target by 40.34% as Yields Fall to 15.89%
The Central Bank of Nigeria (CBN) allotted ₦8.14trillion across eight Nigerian Treasury Bills (NTB) auctions between July and September 2026, exceeding the ₦5.80trillion third-quarter target by 40.34% amid strong investor demand, particularly for 364-day bills. The one-year tenor dominated activity, accounting for ₦7.09trillion or 87% of total allotments, while demand pushed allotments significantly above offer sizes in most auctions.
Despite heavy subscriptions, the 364-day stop rate declined sharply by 181 basis points from 17.70% in July to 15.89% by September following the Central Bank of Nigeria’s (CBN) 350-basis-point Monetary Policy Rate (MPR) reduction to 23%. The largest quarterly allotment occurred on August 12, when ₦1.46trillion was issued against a ₦700billion offer despite a record ₦4.40trillion in bids. The 91-day and 182-day bills attracted relatively lower allotments of ₦722.39billion and ₦333.39billion respectively, highlighting investor preference for longer-duration instruments. With Treasury bill maturities projected at ₦2.64trillion during the quarter, the Debt Management Office (DMO) and Central Bank of Nigeria (CBN) effectively utilized Treasury bills to fund government borrowing needs and manage system liquidity.
EQUITIES MARKET
The Nigerian equities market closed bullish this week as the NGX All-Share Index and Market Capitalization appreciated by 0.92% to close the week at 252,113.41 and ₦163.65trillion respectively compared to at 249,804.56 and ₦162.15trillion last week.
On a sectoral basis, major sectors closed positively, with the Banking, Consumer Goods, Industrial Goods and Oil & Gas indices increasing by 3.06%, 0.62%, 1.56% and 3.49% while the Insurance index closed negatively, declining by 0.52%.
Notable gainers this week were Critical Minerals Financing Corporation PLC and Thomas Wyatt Nigeria PLC while Fidelity Bank PLC and Fortis Global Insurance PLC.
Next week, the equities market is expected to remain positive, supported by demand for quality stocks, although profit-taking and attractive fixed-income yields could keep gains measured.
CURRENCY
| (₦/$) | 25/09/2026 | 18/09/2026 | W-O-W% |
| NAFEM | 1,329.51 | 1,331.20 | -0.13% |
| Parallel | 1,390.00 | 1,390.00 | 0.00% |
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,818.07 | -1.12% |
| EUR/NGN | ₦1,564.91 | -0.72% |
| CAD/NGN | ₦971.14 | -1.02% |
TOP GAINERS
| Ticker | Open | Close | Gain | % |
| CMFC | 2.04 | 3.26 | 1.22 | 59.80% |
| THOMASWY | 2.30 | 2.95 | 0.65 | 28.26 |
| UPDC | 3.10 | 3.85 | 0.75 | 24.19% |
| OMATEK | 1.20 | 1.48 | 0.28 | 23.33% |
| FTGINSURE | 1.65 | 2.00 | 0.35 | 21.21% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| TRANSPOWER | 219.60 | 178.00 | -41.60 | -18.94% |
| JOHNHOLT | 9.00 | 7.30 | -1.70 | -18.89% |
| ELLAHLAKES | 10.20 | 8.35 | -1.85 | -18.14% |
| LIVINGTRUST | 3.15 | 2.60 | -0.55 | -17.46% |
| HMCALL | 3.60 | 3.00 | -0.60 | -16.67% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.