GLOBAL ECONOMY
The US Federal Reserve rose federal funds rate by 25 basis points, a range of 3.75%-4% to combat elevated inflation, with updated projections forecasting 2026 GDP growth at 2.30%, core Personal Consumption Expenditures (PCE) inflation at 3.40%, and an unemployment rate of 4.10%. Despite this tightening, the labour market remained resilient, as initial jobless claims fell to 0.20million and continuing claims dropped to 1.73million. Trade and price pressures persisted, as nonfuel import prices surged 0.70% month-on-month (up 7% annually) and export prices rose 0.60% month-on-month (up 8.60% annually). Meanwhile, geopolitical trade tensions loomed as President Donald Trump threatened sweeping tariffs on the European Union over its proposed associate membership for Canada, adding uncertainty to the global trade outlook.
The British pound hovered near £1/$1.34 after the Bank of England maintained its base rate at 3.75% in a 6-3 vote, while committing to unwind its government bond holdings at an average annual pace of £46billion through 2034. Inflationary concerns remained elevated, with the annual Consumers Price Index (CPI) accelerating to 3.10% in August from 2.90% in July, driven by a surge in motor fuel prices from £1.52 to £1.61 per litre for petrol and from £1.68 to £1.82 per litre for diesel, pushing motor fuel inflation to 23% from 15.50%, while core CPI held steady at 2.60% for the fourth consecutive month and services inflation remained at 3.40%. Producer prices also accelerated, with factory gate prices rising 3.70% from 3.30% year-on-year (Y-o-Y), led by a 49.10% jump in coke and refined petroleum products.
In the Euro area annual inflation accelerated to 3.20% in August from 2.90% in July, driven by a surge in energy inflation from 10.30%, to 14.30% while core inflation edged down to 2.40% from 2.50% and 12-month consumer inflation expectations rose to 3% from the previous 2.90 reading. The external sector remained a strong pillar, with the current account surplus widening to €36.50billion in July from €29.70billion the previous year, supported by a goods surplus of €39.80billion and a services surplus of €19.30billion. Furthermore, the Euro Area recorded a trade surplus of €14.20billion in July, its highest in 9 months, as goods exports surged 9% to €276billion from €253.30billion, outpacing the 7.90% rise in imports to €261.80billion, even as construction output contracted by 2% Y-o-Y higher than the 1.40% decline in June amid ongoing weakness in building activity across major economies.
In China industrial production defied expectations by accelerating to 5.20% Y-o-Y in August from 4.50% , driven by a 6.10% surge in manufacturing output. Credit issuance continued to weaken significantly, with new yuan loans rising by a mere ¥60billion in August, drastically missing the ¥400billion expectation and trailing the ¥590billion recorded the previous year, while broader aggregate financing reached ¥1.66trillion, heavily supported by government bond issuance. Fiscal revenue growth eased slightly to 5.70% from 5.80%, while expenditure growth slowed to 1.20% from 1.30%. Credit demand also remained weak, with the People’s Bank of China (PBOC) describing slower loan growth as the new normal amid weakness in property and local-government borrowing. Policymakers are expected to keep the one-year and five-year Loan Prime Rates unchanged at 3% and 3.50%, respectively, while potential tariff reductions on US LNG could support energy ties and market sentiment.
Next Week global markets are expected to remain cautious as investors assess growth signals from upcoming PMI data, central-bank decisions and persistent inflation and energy-price pressures.
GLOBAL MARKETS
US equities ended the week mixed, as investors grappled with rising interest rate expectations, higher Treasury yields and renewed inflation concerns. Market sentiment deteriorated after stronger-than-expected inflation data showed headline CPI holding at 3.40% Y-o-Y. Compared to last week, the Dow Jones and S&P 500 decreased by 1.70% and 0.14% to close at 51,680.74 and 7,646.04, respectively, while the Nasdaq increased by 0.72% to close at 26,522.55.
European equities ended the week lower, despite a rebound on Friday, as investors weighed rising inflation risks, higher bond yields and the prospect of further monetary tightening from major central banks after European Central Bank (ECB) raised interest rates by 25bps and signalled that inflation could remain elevated for longer amid rising energy costs. Compared to last week, the German DAX and CAC 40 decreased by 1.10% and 1.40% to close at 25,288.03 and 8,065.02 while FTSE 100 1increased by 0.01 to close at 10,651.02 .
Asian equities ended the week mixed, as rising global bond yields, persistent inflation concerns and mounting expectations of further monetary tightening weighed on investor sentiment across the region. Compared to last week, the Hang Seng Index decreased by 0.22% to close at 24,750.78, while the TOPIX Index increased by 1.56% to close at 4,091.14.
Next week, global markets will be driven primarily by US and global PMI data, China’s policy signals, the US–China summit and movements in Treasury yields and the Dollar.
DOMESTIC ECONOMY
Nigeria’s Headline Inflation Eases to 15.39% in August 2026
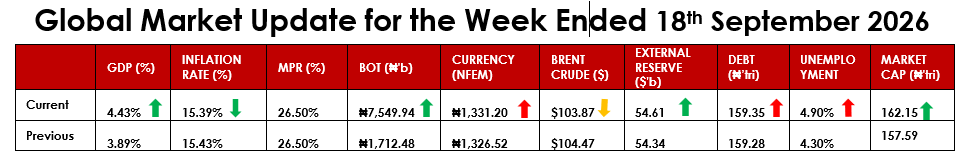
Nigeria’s headline inflation eased marginally to 15.39% in August 2026 from 15.43% in July, extending the disinflation trend for a third consecutive month, while the pace of monthly price increases slowed significantly. Month-on-month headline inflation declined to 0.71% from 1.57%, supported by lower food and core inflation, with food inflation falling to 19.57% Y-o-Y and monthly food inflation dropping to 1.02% from 5.56%; core inflation also declined to 13.29% Y-o-Y, while monthly core inflation turned negative at -0.06%. The 12-month average headline inflation rate fell to 16.30% from 28.32% a year earlier, although rural monthly inflation accelerated to 1.79% from 0.78%, indicating pockets of persistent price pressure. The continued moderation in inflation strengthens the case for a gradual easing of monetary conditions if the trend persists, with potential implications for fixed-income yields and real returns, although the elevated headline and food inflation rates remain relevant constraints on household purchasing power and broader demand.
Nigeria’s Current Account Surplus Rises 67.90% to $7.54billion in Q2 2026
Nigeria’s current account surplus widened 67.9% to $7.54billion in Q2 2026 from $4.49billion in Q1, driven primarily by stronger export receipts and higher remittance inflows. The goods account surplus increased to $10.12billion from $5.96billion, as total exports rose to $20.08billion, supported by higher crude oil, natural gas, refined petroleum products and non-oil exports, while crude oil imports declined to $580million from $1.39billion. Personal transfers also increased 9.81% to $5.82billion, although higher net services outflows and primary income debits, which rose to $4.67billion and $4.20billion respectively, partly offset the improvement. Meanwhile, the financial account reversed to a $1.74billion net lending position from $2.03billion net borrowing in Q1, supported by portfolio investment liabilities of $7.09billion and foreign direct investment inflows of $1.15billion. Overall, the balance of payments recorded a $3.51billion surplus, reinforcing Nigeria’s external position and potentially providing further support for foreign exchange liquidity and Naira stability, alongside continued reserve accumulation.
Nigeria’s Foreign Reserves Rise 30.50% Year-on-year to $54.61billion in September 2026
Nigeria’s gross foreign exchange reserves increased 30.50% Y-o-Y to $54.61billion as of September 14, 2026, strengthening the country’s external liquidity position. Reserves rose by $12.76billion from $41.84billion on September 15, 2025, while adding $707.75million between September 1 and September 14, 2026, and approximately $2.28billion over the past month. The improvement has been supported by stronger foreign capital inflows, with Nigeria attracting $10.37billion in foreign capital in Q1 2026, although the sensitivity of portfolio inflows to global interest rates and exchange-rate expectations remains a potential risk. The higher reserve buffer, which has surpassed the CBN’s projected $51.04billion level for 2026, should strengthen the CBN’s capacity to manage foreign exchange liquidity and support Naira stability, while providing greater resilience against external shocks.
Nigeria’s Portfolio Investment Inflows Rise 14.40% to $6.03billion in Q1 2026
Nigeria’s portfolio investment inflows increased 14.40% to $6.03billion in Q1 2026 from $5.27billion in Q4 2025, making portfolio investment the dominant component of the $7.22billion gross incurrence of financial liabilities. The increase, driven mainly by higher foreign purchases of Nigerian equities, significantly exceeded direct investment liabilities of $1.03billion, highlighting stronger foreign appetite for liquid Nigerian securities relative to longer-term investment. This occurred alongside a 13.26% rise in total FX inflows to $31.34billion and an 11.78% decline in FX outflows to $11.01billion, resulting in a net FX inflow of $20.33billion, while external reserves increased to $48.35billion at end-March 2026. However, the growing concentration of foreign capital in portfolio assets, alongside a 14.08% increase in portfolio investment liabilities to $58.01billion, leaves external financing more sensitive to shifts in global yields, exchange-rate expectations and investor sentiment, with potential implications for Naira liquidity and domestic fixed-income and equity markets.
Next Week Nigerian markets are expected to remain cautious, with focus on the CBN’s 21–22 September MPC meeting, liquidity conditions, Naira stability, fixed-income yields and equity-market positioning.
EUROBOND MARKET
Nigerian sovereign Eurobonds ended the week on a weaker note, as yields edged higher, particularly at the long end, amid tighter global financial conditions and cautious investor positioning. The Eurobond curve averaged around 7.11%–7.12%, while long-dated bonds recorded increases, with the 2051 Eurobond yield rising to 8.31%, up 15.60bps from end-August, while the 2046 and 2049 bonds also moved above 8.20%. The upward pressure was driven largely by the rise in US Treasury yields, with the 10-year Treasury briefly exceeding 5%, alongside the Federal Reserve’s 25bps rate hike to 3.75%–4%.
Next week, Nigeria’s Eurobonds will likely react to US Treasury yields, Federal Reserve rate expectations, oil prices and broader emerging-market risk sentiment.
ALTERNATIVE ASSETS
GOLD
Gold rose 1% week on week (W-o-W) to close at $4,424.90/oz, marking its first weekly gain in four weeks. The recovery reflected short-covering after stronger-than-expected inflation data as the Federal Reserve’s 25bps rate had initially pressured the bullion, while easing oil prices reduced concerns about prolonged inflationary pressure.
OIL
Brent fell 1.50% W-o-W to close at $104.87 per barrel, while WTI declined 0.70% to $100.30 per barrel. Prices weakened as concerns over Saudi supply disruptions eased and reports of additional crude availability outweighed broader Middle East supply risks; US crude inventories also increased during the week. The decline reduced near-term inflation pressure, although elevated prices and unresolved geopolitical risks continued to pose risks to global energy markets.
ETFs
US-listed ETF data showed $15.97billion of net inflows, led by international-equity ETFs at $6.89billion and US fixed-income ETFs at $4.91billion, while international fixed-income ETFs attracted $1.96billion and US-equity ETFs received $0.29billion. Separately, gold funds recorded $3.40billion of inflows, extending their streak to 11 consecutive weeks, while global high-yield bond funds suffered $2billion of outflows, indicating continued demand for defensive and investment-grade exposures alongside caution toward lower-quality credit.
Next week, Federal Reserve expectations, US Treasury yields, the Dollar, Middle East developments, oil-supply risks and further ETF-flow data will remain the major drivers of Gold, Oil and broader alternative-asset market sentiment.
MONEY MARKET AND FIXED INCOME
System liquidity was volatile during the week, opening at a surplus of ₦2.56trillion before rising sharply following ₦3.81trillion in OMO and primary-market repayments. Liquidity climbed to ₦4.89trillion by mid-week as banks received ₦3.06trillion in OMO maturities and ₦748.64billion from primary-market repayments, leading to increased Standing Deposit Facility (SDF) placements. However, subsequent CBN sterilisation through OMO operations reversed the liquidity build-up, with system liquidity falling 65.53% to ₦2.03trillion.
The tighter liquidity position was reflected in funding rates, as the Nigerian Overnight Funding Rate (NOFR) increased to 22.20%, while the Open Repo Rate (OPR) remained at 22% and the interbank overnight rate rose to 22.30% from 22.19%. Meanwhile, average secondary-market T-bill yields edged higher to 18.81% from 18.77%, indicating modest upward pressure on short-term rates.
Domestic FGN bond yields remained volatile between 16.50% and 16.95% across the mid-tenor segment ahead of the September primary market auction, which recorded ₦1.40trillion in subscriptions against ₦1trillion offered, with the Apr-2036 and Apr-2038 bonds clearing at 16.79% and 16.85%, respectively. Meanwhile, Nigeria’s inclusion in the J.P. Morgan GBI-EM Edge Index with a 7.40% weighting marked a significant return to a major emerging-market bond benchmark and could improve visibility among foreign investors, although immediate market reaction remained muted.
Next week, money-market liquidity is expected to remain tight and volatile, with elevated short-term rates driven by CBN sterilisation and interbank demand, although maturities and government inflows could provide temporary liquidity relief.
DOMESTIC MARKETS
EQUITIES MARKET
The Nigerian equities market closed bullish this week as the NGX All-Share Index and Market Capitalization appreciated by 2.78% and 2.90% to close the week at 249,804.56 and ₦162.15trillion respectively compared to at 243,052.74 and ₦157.59trillion last week.
A total turnover of 3.249 billion shares worth ₦237.98billion in 287,919 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 3.6billion shares valued at ₦130.15billion that exchanged hands last week in 244,777 deals.
On a sectoral basis, major sectors closed positive, with the Banking, Insurance, Consumer Goods, Industrial Goods and Oil & Gas indices increasing by 4.43%, 3.79%, 0.52%, 3.12 % and 3.71% respectively.
Notable gainers this week were Updc Real Estate Investment Trust and Sovereign Trust Insurance Plc while Transcorp Power Plc and John Holt Plc topped the losers list.
SUPPLEMENTARY LISTINGS
Abbey Bank Plc: Listing of 26,562,647,265 Ordinary Shares of 50 Kobo Each at ₦2.43 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX) following the Bank’s private placement of 26,562,647,265 ordinary shares at ₦2.43 per share, increasing its issued and fully paid-up share capital from 10,153,846,154 to 36,716,493,419 ordinary shares.
Critical Minerals Financing Corporation Plc: Listing of 1,068,980,259 Ordinary Shares of 50 Kobo Each at ₦1.69 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX) following the conversion of ₦1,806,576,637 debt to equity at ₦1.69 per share, increasing the Company’s issued and fully paid-up share capital from 1,500,660,000 to 2,569,640,259 ordinary shares.
Next week, the NGX is expected to maintain a positive but volatile bias, supported by institutional buying, FTSE Russell-related positioning and the Dangote Refinery IPO, while elevated rates, fixed-income competition, profit-taking and IPO-related liquidity diversion could limit broader market gains.
Currency
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,783.79 | -3.46% |
| EUR/NGN | ₦1,585.70 | -3.52% |
| CAD/NGN | ₦985.14 | -3.44% |
| (₦/$) | 18/09/2026 | 11/09/2026 | W-O-W% |
| NAFEM | 1,331.20 | 1,321.21 | 0.75% |
| Parallel | 1,390.00 | 1,390.00 | 0.00% |
TOP GAINERS
| Ticker | pen | Close | Gain | % |
| UPDCREIT | 13.75 | 18.55 | 4.80 | 34.91% |
| SOVRENINS | 1.68 | 2.20 | 0.52 | 30.95% |
| MBENEFIT | 2.95 | 3.60 | 0.65 | 22.03% |
| NGXGROUP | 148.00 | 179.90 | 31.90 | 21.55% |
| FBNH | 136.00 | 160.00 | 24.00 | 17.65% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| TRANSCORP | 219.60 | 178.00 | -41.60 | -18.94% |
| JOHNHOLT | 9.00 | 7.30 | -1.70 | -18.89% |
| ELLAHLAKES | 10.20 | 8.35 | -1.85 | -18.14% |
| LIVINGTRUST | 3.15 | 2.60 | -0.55 | -17.46% |
| OMATEK | 1.37 | 1.20 | -0.17 | -12.41% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.