GLOBAL ECONOMY
US manufacturing activity remaining firmly in expansion territory as Manufacturing Purchasing Managers’ Index (PMI) rose to 55.50 in October from 54.50, while the S&P Global Manufacturing PMI stood at 54.90, supported by strong demand from artificial intelligence (AI), semiconductors, data centres and infrastructure projects. The labour market remained robust, with nonfarm payrolls increasing by 165,000, unemployment easing to 4.10%, and average hourly earnings rising 0.40% month-on-month to $38. However, inflationary pressures remained evident as tariffs, higher energy and transport costs pushed manufacturing input prices higher and lifted selling prices to their fastest pace since 2022. The US 10-year Treasury yield declined to 4.90%.
The UK economy showed mixed momentum, with the Bank of England (BoE) raising its key interest rate by 25 basis points to 4%, its first hike since 2023, while signaling further tightening may be needed as inflation is projected to rise toward 5% by mid-2027. The Pound Sterling traded near £1/$1.34 after initially rallying on the rate hike. Business activity strengthened, with the Composite Purchasing Managers’ Index (PMI) rising to 52.90, the highest in eight months, supported by Services PMI at 52.80 and Manufacturing PMI at 52.80, indicating continued expansion in private-sector activity. However, domestic demand remained uneven as Construction PMI fell sharply to 43.60.
The Euro traded below €1/$1.12 as stronger US economic data boosted the Dollar. The Eurozone economy showed growing signs of strain as inflation accelerated to a three-year high of 4% in October, driven largely by surging energy costs, while producer prices jumped 11.10% year-on-year and 2.50% month-on-month, reinforcing expectations that the European Central Bank (ECB) may resume policy tightening after keeping its deposit rate at 2.50%. Business activity remained in expansion territory but lost momentum, as the Composite (PMI) eased to 51.70, Services PMI to 51.40, and Construction PMI fell sharply to 42.50, marking a 54th consecutive month of contraction in the sector.
In China, The People’s Bank of China foreign exchange reserves rose by $4.90billion to $3.41trillion in October, while gold holdings increased for a 24th consecutive month to 78.30 million fine troy ounces. The central bank accelerated monetary policy reforms by adopting an overnight policy rate of 1.25% as its primary benchmark and raised the foreign exchange reserve requirement ratio to 6% from 4% to moderate Yuan appreciation. Economic activity slowed modestly, with the Composite PMI easing to 52.00 and Services PMI falling to 50.80, although Manufacturing PMI remained relatively strong at 52.00, marking an eleventh consecutive month of expansion.
Next week, markets will focus on the outcome of the US midterm elections, as investors assess potential policy shifts, regulatory changes and implications for fiscal spending. Attention will also remain on the OPEC meeting, developments in the Middle East and Ukraine, key inflation data.
GLOBAL MARKETS
United States equities ended the week lower as concerns over artificial intelligence (AI) spending and the implications of the US mid-term election outcome weighed on technology stocks, while stronger crude oil prices supported energy shares. Compared with the prior week, the Dow Jones, S&P500 and Nasdaq decreased by 0.94%, 2.68% and 3.37% to close at 51,285.73, 7,376.86 and 24,579.43 respectively.
European equities closed the week mixed as a global technology selloff pressured major indices, while optimism over monetary policy and corporate earnings helped support sentiment. Compared to last week, the German DAX and CAC 40 increased by 0.01% and 2.13% close at 25,820.36 and 8,139.00 while the FTSE100 decreased by 0.52% to close at 10,673.94.
Asian equities ended the week mixed as concerns over returns on artificial intelligence (AI) investments and weakness in global semiconductor stocks weighed on technology-focused markets, while selective bargain hunting supported Hong Kong equities. Compared to last week, the Hang Seng Index increased by 5.10% to close at 24,481.86 while TOPIX Index decreased by 6.48% to close at 3,707.99.
Next week, investors will focus on the United States inflation data and its implications for Federal Reserve (Fed) policy, while monitoring the impact of the recent United States election outcome on market sentiment. Attention will also remain on crude oil prices and geopolitical developments for further direction across global financial markets.
DOMESTIC ECONOMY
Nigeria’s Private Sector Expansion Extends to Five Months as PMI Rises to 53.20, Led by Agriculture and Industry
Nigeria’s private sector maintained its growth trajectory in October 2026, with the Purchasing Managers’ Index (PMI) rising to 53.20 points from 53.00 points in September, marking a fifth consecutive month of expansion. Growth was driven by stronger performances in Agriculture (54.70 points) and Industry (52.60 points), while Services moderated slightly to 52.70 points but remained in expansion territory. The composite output index improved to 54.60 points, while employment strengthened to 53.20 points from 51.50 points, reflecting increased hiring activity. Notably, 24 of 32 subsectors expanded, with Cement Manufacturing (60.20 points) and Educational Services (60.20 points) emerging as the strongest performers. However, rising cost pressures persisted, as the composite input price index increased to 64.00 points and output prices rose to 58.90 points, indicating that while economic activity continues to recover, businesses are still facing elevated operating costs.
Nigeria Commands 16% of Africa’s Corporate Debt as OECD Highlights $4.40trillion Untapped Capital Pool
Nigeria accounted for 16% of Africa’s outstanding corporate debt at the end of 2025, making it the continent’s second-largest corporate debt market behind South Africa (31%), according to the Organisation for Economic Co-operation and Development (OECD). Together with Egypt (13%), Mauritius (9%), Mozambique (6%) and Morocco (5%), the six countries represented 80% of Africa’s corporate debt stock. Despite growing market activity, Africa contributed just 0.40% of global market capitalization, reflecting shallow capital markets and continued reliance on bank lending. In Nigeria, bank loans accounted for 74.20% of the ₦6.25trillion debt held by 19 major listed companies, although alternative financing is gaining traction, with commercial paper issuance rising 40% to ₦1.61trillion in 2025. The OECD noted that Africa holds over $4.40trillion in domestic capital pools, underscoring significant potential to expand long-term investment financing and strengthen economic resilience.
Delta Tops FAAC Allocations at ₦98.27billion as States’ Revenue Surges 52.44%; Lagos Falls to Fifth Despite Record VAT Share
Nigeria’s 36 states received a combined ₦1.07trillion in net allocations from the Federation Account Allocation Committee (FAAC) in August 2026, representing a 52.44% increase from ₦704.01billion a year earlier. Delta State led with ₦98.27billion, followed by Rivers State (₦81.89billion), Bayelsa State (₦78.39billion) and Akwa Ibom State (₦77.75billion), driven largely by oil derivation revenue, while Lagos State dropped to fifth place with ₦43.22billion despite receiving the highest net Value Added Tax (VAT) allocation of ₦34.79billion. The top 10 states accounted for 48.58% of total disbursements and received 95.15% of derivation revenue, underscoring the continued dominance of oil-producing states in revenue allocation, with Delta alone receiving ₦73.57billion in derivation earnings and accounting for 9.16% of total state allocations.
CBN Study Warns ₦29.20trillion Borrowing Plan Could Weigh on Naira and Interest Rates
A study published in the Central Bank of Nigeria (CBN) Journal of Applied Statistics found that persistent budget deficits are a major driver of naira depreciation and place delayed upward pressure on interest rates, reinforcing concerns over Nigeria’s widening fiscal gap. Using data from 1981 to 2024, the research showed that fiscal deficits initially account for 100% of their own variance and still explain about 53% by the tenth period, highlighting their tendency to persist and fuel exchange rate instability. While the study found no statistically significant direct link between deficits and inflation, it noted that price pressures are driven more by exchange-rate pass-through, supply-side shocks and structural bottlenecks. The findings come as the Federal Government’s 2026 budget deficit stands at ₦23.85trillion, with planned borrowing increased to ₦29.20trillion, despite the Central Bank of Nigeria (CBN) cutting the Monetary Policy Rate (MPR) by 350 basis points to 23%. The study recommends stricter fiscal rules, a non-oil stabilisation fund and improved fiscal-monetary coordination to reduce pressure on the naira, interest rates and private-sector investment.
Tinubu Seeks $7.70billion External Borrowing as Nigeria’s Public Debt Climbs to ₦166.79trillion
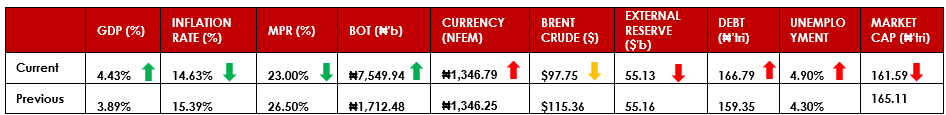
President Bola Tinubu has requested Senate approval for ₦10.79trillion (approximately $7.70billion) in external borrowing to fund part of the Federal Government’s ₦31.40trillion 2026 budget deficit, with total planned borrowing for the year standing at ₦29.20trillion, comprising ₦18.40trillion domestically and ₦10.79trillion externally. The proposed funding, expected to come from sources including Eurobonds, multilateral institutions and the International Monetary Fund (IMF), will support priority sectors such as infrastructure, power, agriculture, healthcare, education and security, while also bolstering foreign exchange reserves. The request comes as Nigeria’s public debt rose to ₦166.79trillion as of June 2026 from ₦159.35trillion in March, with domestic debt accounting for 54.91% of the total, highlighting the government’s growing reliance on borrowing to finance fiscal deficits and development spending.
MSMEs Power Nigeria’s Economy, Contributing 48% of GDP and 87% of Employment
Nigeria’s Micro, Small and Medium Enterprises (MSMEs) remain the backbone of the economy, accounting for 96% of businesses, contributing 48% to Gross Domestic Product (GDP) and providing 87% of national employment, according to Minister of State for Industry, John Owan-Enoh. The government highlighted ongoing efforts to strengthen the sector through support from the Small and Medium Enterprises Development Agency of Nigeria (SMEDAN), Bank of Industry (BOI) and Nigerian Export-Import Bank (NEXIM), alongside initiatives such as the Nigerian Industrialisation Policy, which targets increasing manufacturing’s contribution to GDP to 20%-25% by 2030. Additional investments in electric vehicle infrastructure, skills development and an €85million financing facility for cocoa processing underscore efforts to boost local manufacturing, value addition and small-business growth, reinforcing the sector’s critical role in job creation and economic expansion.
Next week, attention will remain on naira stability, the Federal Government’s borrowing plans and crude oil prices, even as political campaign activities gather momentum, with investors assessing their impact on foreign exchange liquidity, external reserves and overall economic sentiment.
EUROBOND MARKET
Nigeria’s Eurobond market maintained its bullish momentum, with average yields declining by 18 basis points to 7.07% as investors increased demand for the country’s Dollar-denominated sovereign bonds. Buying interest driving gains across the curve and reflecting improving investor confidence in Nigeria’s external debt market. The rally was supported by stronger risk appetite for Nigerian assets and sustained demand for sovereign credit exposure, resulting in broad-based price appreciation across benchmark issues.
Next week, the Nigerian sovereign Eurobond market is expected to remain cautiously positive, supported by continued buying interest and favourable investor sentiment, although global interest-rate expectations may drive selective positioning across maturities.
ALTERNATIVE ASSETS
GOLD
Gold rebounded during the week, with spot prices closing around $4,070.41/oz, supported by safe-haven demand amid geopolitical uncertainty, although gains were restrained by a stronger United States Dollar and elevated bond yields.
OIL
Oil prices remained firm, with Brent crude trading near $97.75/barrel, supported by ongoing Middle East tensions and concerns over global supply disruptions.
ETFs
Commodity Exchange-Traded Funds (ETFs) delivered mixed performance, as energy-focused funds outperformed on stronger oil prices, while precious metals ETFs lagged amid pressure from higher yields and Dollar strength.
Next week, oil prices may remain supported by geopolitical risks, while gold could stay volatile as markets assess United States inflation data and interest rate expectations.
MONEY MARKET AND FIXED INCOME
System liquidity remained robust during the week, closing at a net long position of ₦8.51trillion, supported by sizeable Open Market Operation (OMO) maturities and sustained inflows from maturing government securities. Despite the surplus liquidity, overnight funding rates remained broadly stable around 20%, reflecting balanced interbank market conditions.
The Central Bank of Nigeria (CBN) conducted a ₦1.50trillion OMO auction across the 179-day, 270-day and 361-day tenors, attracting strong investor demand with subscriptions of ₦5.74trillion and total allotments of ₦2.72trillion. Stop rates cleared at 17.25%, 16.54% and 15.74%, respectively, indicating strong appetite for longer-dated bills amid abundant market liquidity.
Meanwhile, the Debt Management Office (DMO) offered ₦800billion at its Nigerian Treasury Bills auction, receiving subscriptions of ₦2.02trillion and allotting ₦509.40billion. Stop rates were maintained at 15.40%, 15.79% and 15.80% across the 91-day, 182-day and 364-day tenors, highlighting sustained investor demand and the authorities’ preference to keep borrowing costs contained.
In the secondary fixed income market, bullish sentiment persisted as strong local and offshore demand met limited supply. Consequently, benchmark bond yields moderated across key maturities, with actively traded mid-tenor bonds closing around the 16.75%-16.85% range.
Next week, liquidity conditions are expected to moderate following the settlement of the OMO auction, although system balances should remain comfortable. Fixed income yields are likely to trade within current levels as investors position ahead of the upcoming Federal Government of Nigeria bond auction.
EQUITIES MARKET
The Equities market closed bearish this week as the NGX All-Share Index and Market Capitalization depreciated by 2.13% to close the week at 248,877.22 and ₦161.59trillion compared to 254,299.49 and ₦165.11trillion last week.
A total turnover of 2.01 billion shares worth ₦148. billion148.74billion in 191,325 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 7.62 billion shares valued at ₦637.826 billion637.826billion that exchanged hands last week.
On a sectoral basis, major sectors closed negatively, with the Consumer Goods, Banking, Insurance Industrial Goods and Oil and Gas indices decreasing by 1.41%, 2.45%, 0.03%, 4.35% and -3.72%.
This week, notable gainers were Honeywell Flour Mills Plc and Transnational Corporation Power Plc while Vitafoam Nigeria Plc and Sovereign Trust Insurance Plc topped the losers list.
Going forward, the Nigerian equities market is expected to remain positive in the medium term, supported by bargain-hunting in fundamentally strong stocks, corporate earnings and dividend expectations.
CURRENCY
| 06/11/2026 | 30/10/2026 | W-O-W % | |
| NAFEM | 1,346.79 | 1,346.25 | 0.04% |
| Parallel | 1,385.00 | 1,389.00 | -0.29% |
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,836.49 | +0.17% |
| EUR/NGN | ₦1,532.08 | +0.28% |
| CAD/NGN | ₦974.67 | -0.50% |
TOP GAINERS
| Ticker | Open | Close | Loss | % |
| HONYFLOUR | 22.55 | 29.50 | 6.95 | 30.82% |
| TRANSPOWER | 178.00 | 219.60 | 41.60 | 23.37% |
| ETRANZACT | 16.30 | 18.65 | 2.35 | 14.42% |
| MANSARD | 10.75 | 11.80 | 1.05 | 9.77% |
| TIP | 24.55 | 26.90 | 2.35 | 9.57% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| VITAFOAM | 174.60 | 141.50 | -33.10 | -18.96% |
| SOVRENINS | 2.35 | 1.95 | -0.40 | -17.02% |
| ETERNA | 42.75 | 36.00 | -6.75 | -15.79% |
| ABCTRANS | 6.60 | 5.70 | -0.90 | -13.64% |
| INTENEGINS | 1.95 | 1.70 | -0.25 | -12.82% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.