GLOBAL ECONOMY
The US economy expanded at an annualised rate of 3.40% in Q3 2026, up from 2.20% in Q2 and above expectations of 3.20%, driven by a sharp acceleration in private domestic investment, particularly AI-related equipment spending, while consumer spending remained robust at 3.80%. However, inflationary pressures intensified, with headline Personal Consumption Expenditures (PCE) inflation accelerating to 3.60% year-on-year in September from 3.40% in August, while core PCE rose to 3.10% from 3%, remaining above the Federal Reserve’s 2% target. The Fed held its policy rate at 3.75%–4% in October following September’s 25-basis-point increase, citing resilient economic activity and elevated inflation.
The British Pound rose above £1/$1.34, reaching its highest level since mid-September and gaining approximately 1% in October, its first monthly advance since August, supported by expectations of tighter monetary policy following the government’s budget. Markets are pricing in a Bank of England rate hike on 5 November, with further increases anticipated in February and July, amid persistent inflation and stronger-than-expected economic data. Meanwhile, the Office for Budget Responsibility revised its public borrowing forecasts upwards, projecting borrowing at 4.20% of GDP this year, compared with its previous estimate of 3.60%, before declining to 3.40% next year and 2.90% in 2028–29, reflecting elevated energy prices, inflation and borrowing costs.
The Eurozone economy expanded by 0.40% in Q3 2026, slowing from 0.60% in Q2 but exceeding expectations of 0.20%, while annual growth accelerated to 1.30% from 1.20%, its strongest pace in over a year. Growth was uneven across the bloc, with Ireland recording the strongest quarterly expansion at 5.50%, while Germany grew by 0.20%, France contracted by 0.10% and Italy stagnated. Labour market conditions weakened, as the unemployment rate remained at 6.50% for the third consecutive month, its highest level since February 2024, compared with 6.30% a year earlier, while the number of unemployed rose by 122,000 to 11.56million. The European Central Bank held its rates at 2.65% and 2.50%, respectively, citing persistent energy-driven inflation risks alongside concerns about economic growth, although policymakers discussed a possible rate hike.
China’s economic activity weakened with the official manufacturing Purchasing Managers’ Index (PMI) falling to 49.30 from 50.10 in September, below market expectations of 50.00, while the non-manufacturing PMI declined to 49.70 from 50.20, also missing forecasts of 50.50. The readings indicate renewed contraction across both manufacturing and services, partly reflecting seasonal disruptions from the Golden Week holiday and subdued domestic and external demand. Manufacturing output fell to 49.30 from 50.10, while new orders declined to 49.40 from 50.50 and export orders dropped to 48.70 from 50; services new orders also weakened to 44.40 from 46.50. Consequently, the composite PMI fell to 49.70 from 50.70, marking the fifth contraction in overall business activity this year.
Next week, markets will focus on the US midterm elections and their implications for President Trump’s legislative agenda, developments in the Middle East and Ukraine, major corporate earnings, the OPEC meeting and key US economic releases.
GLOBAL MARKETS
US equities closed the week mixed as concerns over rising AI infrastructure spending costs. However, energy shares outperformed on stronger crude prices. Compared with the prior week, the Dow Jones, S&P500 and Nasdaq decreased by 0.85%, 0.57% and 2% to close at 51,770.31, 7,580.07 and 25,437 respectively.
European equities ended the week higher, as supportive corporate earnings, expectations of progress toward an Iran peace deal, and resilience in select defensive sectors offset concerns over elevated AI infrastructure spending and a late-week technology-led selloff. Compared to last week, the German DAX, CAC 40 and FTSE100 increased by 2.53%, 2.40% and 0.37% to close at 25,818.21, 7,969.42 and 10,729.78 respectively.
Asian equities ended the week mixed, as concerns over the returns on heavy AI-related investment and a global semiconductor selloff weighed on technology-exposed markets, particularly in Japan, South Korea and mainland China. Compared to last week, the Hang Seng Index increased by 0.87% to close at 23,294.42 while TOPIX Index decreased by 0.25% to close at 2,738.65.
Next week, investors will focus on the impact of the Federal Reserve’s rate decision, key inflation data and corporate earnings, while monitoring China’s growth outlook, Eurozone economic activity and geopolitical developments for clues on the direction of global markets.
DOMESTIC ECONOMY
Nigeria Targets Single-Digit Inflation by End-2027 to Reduce Borrowing Costs
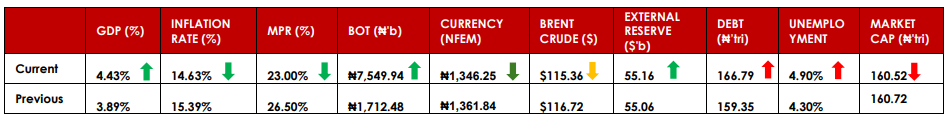
Finance Minister Taiwo Oyedele has reaffirmed the Federal Government’s ambition to reduce inflation to low single digits by the end of 2027, with the objective of creating room for significantly lower interest rates, reducing borrowing costs and stimulating economic growth. Speaking at the Nigeria Economic Summit on 26 October, he highlighted the disparity between Nigeria’s economic growth rate of 4.43% and borrowing costs of nearly 30%, noting that access to single-digit borrowing rates could significantly improve investment prospects and economic output. He added that lower inflation and interest rates would help household incomes grow faster than prices, ease cost-of-living pressures and encourage private sector investment.
Tinubu Seeks National Assembly Approval for $21.70billion External Borrowing Plan President Bola Tinubu has requested National Assembly approval for a supplementary external borrowing plan totaling approximately $21.70billion for 2026–2027, comprising $20.52billion and €1.05billion (approximately $1.17billion). The proposed borrowing is intended to bridge the country’s infrastructure financing gap and fund projects across key sectors, including transportation, agriculture, healthcare, education, water supply, security and employment generation. According to the President, the external financing will support the implementation of critical development projects and accelerate economic growth.
Nigeria’s Portfolio Investment Inflows Rise 17.60% to $7.09billion in Q2 2026
Nigeria’s portfolio investment inflows increased by 17.60% quarter-on-quarter to $7.09billion in Q2 2026, from $6.03billion in Q1, driven largely by higher investments in long-term Federal Government debt securities, according to the Central Bank of Nigeria (CBN). Direct investment liabilities rose by 11.70% to $1.15billion from $1.03billion, while other investment liabilities more than doubled to $2.75billion from $1.36billion, reflecting increased government and private-sector loan drawdowns as well as higher currency and deposit liabilities. Consequently, net incurrence of financial liabilities increased to $10.84billion from $8.36billion. Despite stronger portfolio inflows, total foreign exchange inflows declined by 4.24% to $30.03billion from $31.36billion, as inflows through the CBN fell by 20.47% to $8.12billion, partly offset by a 3.59% increase in autonomous inflows to $21.91billion. External reserves nevertheless rose to $51.39billion at end-June from $48.35billion at end-March, while the average NFEM exchange rate strengthened to ₦1,365.95/$ from ₦1,384.48/$.
World Bank Warns Rising Energy Costs Could Push Global Food Prices Up 7% in 2027 The World Bank projects global food commodity prices to increase by 7% in 2027, following an expected 10% rise in 2026, with grain prices forecast to climb by 9% as higher energy costs, weather-related supply pressures and export disruptions weigh on global markets. According to its latest Commodity Markets Outlook, rising energy prices and disruptions to food exports through the Black Sea are expected to exert greater upward pressure than the early effects of El Niño on tropical commodity supplies. Although favourable harvests are expected to support overall grain availability, with total supplies in the 2026–2027 season projected to be 3% above the 2024–2025 level, adverse weather conditions could still trigger sharper price increases in vulnerable markets. In contrast, beverage prices are projected to decline by 24% in 2026 as cocoa and coffee production recovers, before stabilising broadly in 2027. The broader agricultural commodity price index is expected to rise by 5% in 2027. For Nigeria, the outlook presents a potential source of imported inflationary pressure, although domestic headline inflation eased to 14.63% in September 2026 from 15.39% in August, while food inflation stood at 19.59% year-on-year. The World Bank also forecasts Brent crude prices to moderate to an average of $79 per barrel in 2027 from $91 per barrel in 2026, as rising global supply eases market tightness.
Next week, investors will monitor foreign exchange market movements, external reserves, liquidity conditions and developments in the domestic fixed-income market, particularly Treasury bill auction results and yields.
EUROBOND MARKET
Nigeria’s Eurobond market extended its bullish momentum, with average yields declining by 6bps to 6.89% as investors increased demand for the country’s Dollar-denominated sovereign bonds across the yield curve. The rally was supported by improving macroeconomic fundamentals, including external reserves of about $55.26 billion and a stronger Naira on the official market, and September headline inflation falling to 14.63% from 20.98% a year earlier. The Debt Management Office’s daily trading data also confirmed active secondary-market activity through 29th October,while reports indicated a fourth consecutive session of yield declines, underscoring improved investor confidence in Nigeria’s external-debt profile and credit outlook.
Next week, Nigerian sovereign Eurobond market is expected to maintain a cautiously positive tone next week, supported by renewed buying interest and improving sovereign credit sentiment.
ALTERNATIVE ASSETS GOLD
Gold prices declined sharply during the week, with spot prices falling to $3,885.70 per ounce on 30th October, their lowest level since October 2025. The decline was driven by a stronger US Dollar, elevated bond yields and expectations of tighter US monetary policy, which weakened demand for non-yielding bullion
OIL
Oil prices strengthened amid escalating Middle East tensions and concerns over potential supply disruptions. Brent crude rose to $115.36 per barrel on 28th October, supported by geopolitical risk premiums and uncertainty surrounding supplies through the Strait of Hormuz
ETFs
Commodity ETFs recorded mixed performance, with energy-focused funds outperforming amid rising oil prices, while gold and silver ETFs declined following weakness in precious metals. The divergence reflected shifting investor preference towards energy assets amid heightened geopolitical uncertainty.
Next week, Gold is expected to remain under pressure amid elevated US yields and a stronger Dollar, while crude oil prices may stay elevated due to geopolitical tensions and supply concerns; consequently, energy-focused ETFs are likely to outperform precious metals ETFs in the coming week.
MONEY MARKET AND FIXED INCOME
System liquidity improved to a net long position of ₦8.05trillion from ₦6.66trillion in the previous week, supported by OMO maturities of ₦2.13trillion and net Treasury bill maturities of ₦320.95billion. However, the overnight interbank rate increased by 2bps week-on-week to 20.40%.
During the week the CBN offered ₦1trillion in OMO bills on 29 October, attracting ₦2.28trillion in subscriptions but allotting ₦244.93billion, with stop rates settling at 17.69% and 17.63% for the 124-day and 138-day tenors, respectively.
The DMO also offered ₦800billion in Treasury bills at its 28 October auction, attracting subscriptions of ₦1.91trillion but allotting only ₦71.16billion after rejecting approximately 96% of bids. Stop rates declined by 10bps, 1bp and 10bps to 15.40%, 15.79% and 15.80% across the 91-day, 182-day and 364-day tenors, respectively, reflecting the authorities’ preference for lower borrowing costs.
Next week, the Nigerian money market is expected to maintain elevated liquidity levels, supported by maturing OMO bills and government securities, although further CBN liquidity mop-up operations could moderate the surplus.
EQUITIES MARKET
The Equities market closed bullish this week as the NGX All-Share Index and Market Capitalization appreciated by 2.86% to close the week at 254,299.49 and ₦165.11trillion compared to 247,222.27 and ₦160.52trillion last week.
A total of 1.34million units valued at ₦512.14million were traded this week in 4,472 deals compared with a total of 1.12million units valued at ₦244.25million, transacted last week in 3,298 deals.
On a sectoral basis, major sectors closed negatively, with the Consumer Goods, Banking and Insurance indices decreasing by -0.02%, -3.42% and -2.13% while only the Industrial Goods and Oil and Gas indices closed positive increasing by 14.58% and 0.82%,
This week, notable gainers were Dangote Cement Plc and Honeywell Flour Mill Plc while Caverton Offshore Support Group Plc and Livestock Feeds Plc topped the losers list.
Going forward, the Nigerian equities market is expected to maintain a cautiously positive bias, supported by bargain-hunting and renewed interest in fundamentally strong stocks.
CURRENCY
| 30/10/2026 | 23/10/2026 | W-O-W % | |
| NAFEM | 1,346.25 | 1,361.84 | –1.14% |
| Parallel | 1,389 | 1,390 | –0.07% |
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,822.43 | +0.61% |
| EUR/NGN | ₦1,525.80 | +0.14% |
| CAD/NGN | ₦974.08 | +0.56% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| DANGCEM | ₦1,111 | ₦1,420 | ₦309 | 27.81% |
| HONEYFLOUR | ₦17.90 | ₦22.55 | ₦4.65 | 25.98% |
| UPDCREIT | ₦17.50 | ₦21.10 | ₦3.60 | 20.57% |
| SOVEREIGNINS | ₦1.95 | ₦2.35 | ₦0.40 | 20.51% |
| ETERNA | ₦38.90 | ₦42.75 | ₦3.85 | 9.90% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| CAVERTON | ₦4.80 | ₦3.60 | -₦1.20 | -25.00% |
| LIVESTOCK | ₦17.05 | ₦13.30 | -₦3.75 | -21.99% |
| AUSTINLAZ | ₦2.85 | ₦2.35 | -₦0.50 | -17.54% |
| FIRSTHOLDCO | ₦144.10 | ₦119.15 | -₦24.95 | -17.31% |
| GUINEAINS | ₦0.93 | ₦0.77 | -₦0.16 | -17.20% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.