GLOBAL ECONOMY
US headline inflation held steady at 3.40% Year-on-Year (YoY) while core inflation eased to 2.40%, its lowest level since March 2021, while core CPI rose 0.30%, exceeding expectations. Producer price pressures remained elevated, with annual PPI accelerating to 5.40% from 4.80%, supported by a 24.10% surge in diesel fuel prices, although core PPI moderated to 0.20% Month-on-Month (MoM). Labor market conditions also remained firm, with initial jobless claims edging down to 206,000 and continuing claims falling to 1.77 million, reinforcing expectations that the economy remains near full employment. US crude inventories declined by approximately 0.39 million barrels, extending a broader drawdown trend, while crude production increased to 13.86 million bpd. Meanwhile, wholesale inventories rose 1.30% MoM and 5.70% YoY, indicating continued stock accumulation amid solid business activity.
The UK economy expanded by 0.40% MoM in July 2026, accelerating from 0.30% in June and outperforming expectations of no growth, with services (0.40%), production (0.20%) and construction (0.10%) all contributing to the strongest monthly expansion since February. Annual GDP growth accelerated to 1.60%, the highest since February 2025, supported by a rebound in manufacturing output, which rose 0.90% MoM and 2.60% YoY, led by computer, electronics and optical products (5.20%), basic metals (2.80%) and refined petroleum products (1.20%). External trade also improved, with the UK trade deficit narrowing to £3.45billion in July from £5.54billion, as exports increased 2.10% to £81.92billion while imports fell 0.40% to £85.37billion. Goods exports rose 4.40% to £34.41billion, driven mainly by machinery and transport equipment, while goods imports declined 1.10% to £55.37billion.
The Eurozone annual GDP growth accelerated to 1.20% from 0.60% in Q1. Growth strengthened in Germany (1.00% vs 0.70%) and Italy (1.00% vs 0.80%), remained robust in Spain (2.70%), and slowed in France (0.50% vs 0.70%). The labor market remained resilient despite economic headwinds, with employment increasing 0.10% QoQ to 176.45 million people, while annual employment growth held steady at 0.50%. European Central Bank (ECB) increased its main refinancing rate by 25bps to 2.65% and its deposit rate to 2.50% and raising projections for 2027 to 2.50% and 2028 to 2.10%.
China’s foreign exchange reserves increased to $3.44trillion in August 2026 from $3.42trillionn in July, supported by a 0.50% appreciation of the Yuan against the US Dollar and a 0.40% decline in the Dollar against major currencies, while the People’s Bank of China extended its gold-buying streak to 22 consecutive months, raising holdings to 76.73 million troy ounces and lifting the value of gold reserves to a record $350.08billion from $306.35billion. China’s trade surplus also widened to $119.09billion from $101.01billion a year earlier as exports jumped 25% YoY to $401.44billion, driven by the global artificial intelligence infrastructure boom. Imports also remained robust, rising 28.20% YoY to $282.36billion, supported by stronger demand for crude oil, iron ore and regional manufactured goods.
Next week, attention will center on the Fed’s rate decision, major economic data from China, the Eurozone and the UK, alongside developments in Middle East tensions and global energy markets.
GLOBAL MARKETS
US equities closed the week lower as investors grappled with rising interest rate expectations, higher Treasury yields and renewed inflation concerns. Market sentiment deteriorated after stronger-than-expected inflation data showed headline CPI holding at 3.40% YoY. Compared to last week, the Dow Jones, Nasdaq and S&P 500 decreased by 1.57%, 0.66% and 0.80% to close at 52573.29, 26,333.04 and 7,656.98 respectively.
European equities ended the week lower despite a rebound on Friday, as investors weighed rising inflation risks, higher bond yields and the prospect of further monetary tightening from major central banks after ECB raised interest rates by 25bps and signalled that inflation could remain elevated for longer amid rising energy costs. Compared to last week, the German DAX, CAC 40 and FTSE 100 decreased by 1.83%, 1.20% and 1.67% to close at 25,568.56, 8,179.77 and 10,650.44 respectively.
Asian equities ended the week on a weaker note, as rising global bond yields, persistent inflation concerns and mounting expectations of further monetary tightening weighed on investor sentiment across the region. Compared to last week, the Hang Seng and Topix Indices decreased by 3.30% and 1.83% to 24,805.63 and 4,028.30 respectively.
Next week, global markets will focus on the FOMC Meeting, with investor sentiment likely to be driven by the Fed’s rate decision, policy outlook, Treasury yield movements and inflation expectations.
DOMESTIC ECONOMY
Nigeria’s Trade Hits ₦41.44Trillion as Exports Surge 27.64%, Food Imports Reach ₦3.30Trillion and Asia Leads Trade Flows
Nigeria’s merchandise trade climbed to ₦41.44trillion in Q2 2026, rising 19.13% quarter-on-quarter and 5.61% year-on-year, driven by exports of ₦27.02trillion which accounted for 65.20% of total trade, while imports stood at ₦14.42trillion. Despite maintaining a strong trade surplus, the country spent ₦3.30trillion on food and beverage imports in the first half of 2026, with the import bill jumping from ₦1.39trillion in Q1 to ₦1.91trillion in Q2. Crude oil remained Nigeria’s largest export commodity at ₦12.91trillion, representing 47.79% of exports, while India emerged as the biggest individual export destination with ₦3.29trillion worth of imports from Nigeria. Asia remained Nigeria’s largest trading region, accounting for 59.37% of imports and 32.29% of exports, while exports to the Economic Community of West African States (ECOWAS) reached ₦3.75trillion, representing 56.39% of Nigeria’s exports to Africa. The data highlights strengthening external trade performance and foreign exchange earnings but also underscores persistent dependence on imported food products amid food security concerns, with the Food and Agriculture Organization (FAO) warning that 34.70 million Nigerians could face severe food insecurity during the next lean season.
China, India and Economic Community of West African States Drive ₦14.65Trillion Trade as Nigeria’s Top 10 Trade Partners Hit ₦26.47Trillion in Q2 2026
Nigeria’s total trade with its top 10 partners rose to ₦26.47trillion in Q2 2026, up 9.70% quarter-on-quarter and 4.00% year-on-year, with China retaining its position as the largest trading partner at ₦6.42trillion, followed by India at ₦4.21trillion and the Economic Community of West African States (ECOWAS) at ₦4.02trillion. Notably, trade with ECOWAS surged 77.20% quarter-on-quarter and 103.30% year-on-year, highlighting the growing importance of regional markets for Nigerian exports. While China remained Nigeria’s biggest trade relationship, it also accounted for the country’s largest trade deficit of ₦5.41trillion due to imports worth ₦5.92trillion. Meanwhile, trade with the United States and France declined by 31.30% and 34.60% respectively, while the United Kingdom recorded a strong 94.10% quarterly increase to ₦1.20trillion, re-entering the top 10 rankings. The data underscores Nigeria’s continued reliance on crude oil exports and imported manufactured goods, with manufactured imports rising 16.90% year-on-year to ₦18trillion in H1 2026 and passenger vehicle imports surging 145.60% to ₦1.18trillion, reinforcing concerns about the economy’s persistent import dependence despite efforts to boost domestic manufacturing and regional trade integration.
Nigeria’s Business Confidence Hits 6-Month High as Manufacturing Surges to 120.40 Points, Economic Outlook Strengthens
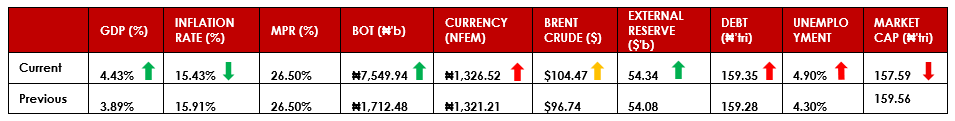
Nigeria’s business confidence improved further in August 2026, with the Nigerian Economic Summit Group (NESG) Current Business Performance Index rising to 112.70 points from 108.60 points in July, driven by stronger demand, exports, cash flow, employment and credit access. Manufacturing led the expansion, with its index climbing to 120.40 points, while Services and Agriculture remained resilient at 112.40 points and 110.50 points, respectively. Business optimism also strengthened, with the Future Business Expectation Index increasing to 129.30 points, although elevated operating costs, financing constraints and power challenges continued to weigh on businesses. The data aligns with Nigeria’s improving economic momentum, supported by 4.43% GDP growth in Q2 2026 and a 52.70-point PMI.
Cash Outside Banks Falls to 8-Month Low of ₦4.80Trillion as Bank Reserves Surge by ₦2.73Trillion in July 2026
Currency held outside Nigeria’s banking system declined for the second consecutive month to ₦4.80trillion in July 2026, its lowest level since November 2025, dropping by ₦118.70billion or 2.40% from ₦4.92trillion in June and by ₦450.20billion or 8.60% from ₦5.25trillion in January. The decline coincided with a 2.50% reduction in total currency in circulation to ₦5.38trillion and a sharp 8% increase in bank reserves from ₦34trillion to ₦36.73trillion, indicating that more liquidity is being retained within the formal banking system. Despite the decline, cash outside banks still accounts for the majority of currency in circulation, although the trend supports the Central Bank of Nigeria (CBN)’s push toward digital payments and financial inclusion. The apex bank is targeting cash outside banks to fall below 40% of total currency in circulation while expanding financial inclusion to 95% of Nigeria’s adult population by 2028, reflecting growing adoption of electronic payment channels, mobile money, fintech services, and digital banking across the country.
Nigeria’s Economic Activity Accelerates as Composite Purchasing Managers’ Index Hits 52.70, Agriculture Extends 25-Month Growth Streak
Nigeria’s economic activity expanded for the third consecutive month in August 2026, with the Composite Purchasing Managers’ Index (PMI) rising to 52.70 points from 51.10 points in July, signaling stronger business conditions across the economy. Growth was driven by the Agriculture sector (53.40 points) and Services sector (53.30 points), while the Industry sector returned to expansion at 50.60 points after months of contraction. Agriculture maintained its impressive 25-month expansion streak, with all subsectors recording growth, while services expanded for a second straight month as business activity recovered. Key indicators remained firmly in expansion territory, including Output (53.90 points), Employment (52.40 points), New Orders (51.80 points) and Stock of Raw Materials (51.60 points), reflecting improving demand, hiring and production activity. The positive momentum aligns with recent private-sector surveys and Nigeria’s 4.43% Gross Domestic Product (GDP) growth in Q2 2026, reinforcing expectations of stronger economic performance in 2026, supported by resilient agriculture, recovering services and a gradually stabilising industrial sector.
Next week, investor sentiment will focus on the August inflation report from the National Bureau of Statistics (NBS), while strong external reserves continue to support confidence in the economy.
EUROBOND MARKET
Nigeria’s sovereign Eurobond market traded weaker through the week, with yields rising across most maturities as subdued investor sentiment weighed on demand for the country’s Dollar-denominated debt securities. The bearish tone pushed the average Eurobond yield up by 13bps WoW to 7.05%, reflecting increased risk aversion along the yield curve and softer appetite for emerging market assets. Despite Nigeria’s improving macroeconomic fundamentals, investors remained cautious amid prevailing global market uncertainties and elevated external financing conditions.
Next week, Nigeria’s Eurobonds are likely to remain sensitive to global interest rate expectations with elevated US Treasury yields and external market volatility continuing to weigh on demand for Nigeria’s dollar-denominated debt.
ALTERNATIVE ASSETS
GOLD
Gold declined about 1.00% WoW to $4,350.00/oz, pressured by a stronger US dollar and rising Treasury yields as markets increased expectations of a Federal Reserve rate hike. Safe-haven demand linked to geopolitical tensions helped limit losses.
OIL
Oil recorded a strong weekly gain, with Brent rising roughly 9% to $104.61 per barrel and WTI advancing 9.70% to $100.05 per barrel, driven by continued concerns over supply disruptions in the Middle East and shipping risks in the Strait of Hormuz.
ETFs
ETF flows remained defensive, with investors favoring fixed-income and commodity funds. Bond ETFs attracted about $12.27billion in inflows, commodity ETFs gained $2.57billion, while overall ETF net issuance remained strong at $33.23billion
Next week, the Fed’s policy decision, US inflation trends, Middle East developments and ETF flows will remain key drivers of Gold, Oil and broader market sentiment.
MONEY MARKET AND FIXED INCOME
System Liquidity remain steadily robust during the week as it opened at a credit of ₦4.27trillion a decline of ₦393.32billion from previous Friday. Tuesday saw a marginal increase of ₦8.97billion and Wednesday saw a decline of ₦1.12trillion following Tuesday’s Net OMO settlement. Thursday saw a Marginal increase also, but Liquidity declined on Friday by ₦763.07billion to close the week at ₦2.46trillion.
Nigeria’s fixed-income market maintained a bullish tone during the week as strong investor demand drove further yield compression across government securities. At the primary market, the Central Bank of Nigeria (CBN) allotted ₦1.05trillion in Treasury Bills against subscriptions of ₦2.64trillion, with demand heavily concentrated on the 364-day tenor, whose stop rate declined by 22bps to 16.62%, marking the third consecutive rate cut. The CBN’s OMO auction also attracted robust demand, receiving ₦6.31trillion in subscriptions against a ₦1trillion offer and resulting in ₦4.40trillion allotments, while stop rates moderated across all maturities. In the secondary market, sustained local and offshore demand supported buying interest in NTBs, OMO bills and FGN Bonds, leading to declines in average NTB and OMO yields to 18.80% and 20.40%, respectively, while bond yields also trended lower. Consequently, the Nigerian Overnght Financing Rate (NOFR) maximum rate increased by 256bps to 27%, the NOFR weighted average and Minimum rate were unchanged at 22% and 20.25% respectively.
Next week, we expect current sentiments to persist in the domestic fixed-income markets although continued CBN OMO liquidity sterilisation could keep money-market rates elevated and moderate the pace of further yield declines.
DOMESTIC MARKETS
EQUITIES MARKET
The Nigerian equities market closed bearish this week as the NGX All-Share Index and Market Capitalization depreciated by 1.60% and 1.24% to close the week at 243,052.74 and ₦157.59trillion respectively compared to at 246,992.44 and ₦159.56trillion last week.
A total turnover of 3.65 billion shares worth ₦130.15billion in 244,777 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 4.36 billion shares valued at ₦210.33billion that exchanged hands last week in 223,284 deals..
On a sectoral basis, major sectors closed mixed, with the Banking, Insurance, Consumer Goods and Industrial Goods indices decreasing by -4.07%, -5.52%, -2.55% and -3.36% respectively, while the Oil & Gas Index increased by 2.83%.
Notable gainers this week were Nigerian Exchange Group PLC and Ellah Lakes PLC, while Fortis Global Insurance PLC and Critical Minerals Financing Corp PLC topped the losers list.
SUPPLEMENTARY LISTINGS
Dangote Sugar Refinery Plc: Listing of 8,097,918,827 Ordinary Shares of 50 Kobo Each at N60.00 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX) from the Company’s Rights Issue of 8,097,918,827 ordinary shares of 50 Kobo each at N60.00 per share on the basis of two (2) new ordinary shares for every existing three (3) ordinary shares held as at the close of business on Monday, 20 April 2026.
The total issued and fully paid-up share capital of Dangote Sugar Refinery Plc has now increased from 12,146,878,241 to 20,244,797,068 ordinary shares of 50 Kobo each.
Next week, the Nigerian equities market is expected to remain cautious as investors continue to rebalance portfolios ahead of the Dangote Refinery IPO, with profit-taking and liquidity rotation likely to pressure sentiment while creating selective opportunities in fundamentally strong stocks.
CURRENCY
| (₦/$) | 11/09/2026 | 04/08/2026 | W-O-W% |
| NAFEM | 1,326.52 | 1,321.21 | 0.40% |
| Parallel | 1,395.00 | 1,390.00 | 0.36% |
| Currency Pair | Exchange Rate | Change |
| BP/NGN | ₦1,847.75 | -0.31% |
| EUR/NGN | ₦1,585.70 | -0.38% |
| CAD/NGN | ₦985.14 | -0.56% |
TOP GAINERS
| TICKER | OPEN | CLOSE | CHANGE | % |
| NGXGROUP | 130.00 | 148.00 | 18.00 | 13.85% |
| ELLAHLAKES | 9.00 | 10.20 | 1.20 | 13.33% |
| SEPLAT | 13,552.60 | 14,907.80 | 1,355.20 | 10.00% |
| ETRANZACT | 12.30 | 13.00 | 0.70 | 5.69% |
| IKEJAHOTEL | 42.55 | 44.50 | 1.95 | 4.58% |
TOP LOSERS
| TICKER | OPEN | CLOSE | CHANGE | % |
| FORTISINS | 2.00 | 1.45 | -0.55 | -27.50% |
| CMFC | 2.64 | 2.00 | -0.64 | -24.24% |
| AUSTINLAZ | 2.50 | 1.99 | -0.51 | -20.40% |
| OMATEK | 1.70 | 1.37 | -0.33 | -19.41% |
| ROYALEX | 1.10 | 0.90 | -0.20 | -18.18% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.