GLOBAL ECONOMY
The US Inflationary pressure intensified as annual headline Consumer Price Index (CPI) rose to 3.70% from 3.40% in August, core inflation accelerated to 2.60%, and annual producer price inflation reached 6.30%, driven by a 10.80% monthly surge in energy costs. The Federal Reserve maintained a cautious stance following its September rate hike to 3.75%–4%, as persistent inflation reduced expectations of further tightening. Meanwhile, the Federal Government recorded a $27billion budget deficit in September, bringing the FY2026 deficit to $1.99trillion, while net foreign capital inflows reached $199.80billion in August.
The UK economy expanded 0.10% month-on-month in August 2026, defying expectations of a 0.10% contraction, while annual Gross Domestic Product (GDP) growth accelerated to 2.10% from 1.80% in July. Industrial production rose 0.80%, its strongest monthly increase since November 2025, driven by a 1.20% rise in manufacturing output, while construction remained weak, declining 0.20% month-on-month and 1.80% year-on-year. The trade deficit narrowed to £0.92billion in August from £2.32billion in July, as exports increased 0.10% and imports fell 1.50%. Stronger-than-expected economic data lifted sterling to a three-week high of around $1.33/£1 and reinforced market expectations of a possible 25-basis-point Bank of England rate hike in November amid persistent inflation risks.
The Euro Area faced intensifying inflationary pressures and weakening industrial activity, with annual inflation accelerating to 3.80% in September 2026 from 3.20% in August, its highest level since September 2023, driven by energy inflation rising to 18.90% and core inflation increasing to 2.50%. Industrial production fell 0.50% month-on-month in August, marking its third consecutive monthly decline, while annual output contracted 1.10%, reflecting weakness across major economies, particularly Italy, where production declined 1.30%. The region also recorded a €16.10billion trade deficit in August, its widest since January 2023, as imports surged 16.70% year-on-year to €243.80billion, outpacing the 9.90% increase in exports to €227.70billion, largely due to higher petroleum and manufactured goods imports amid Middle East supply disruptions. The Euro traded around $1.12/€1, remaining under pressure from US dollar strength and political uncertainty in France.
China’s economy recorded strong external trade performance in September 2026, with exports surging 36.30% year-on-year to a record $447.18billion and imports rising 31% to $313.66billion, expanding the trade surplus to $133.53billion. Export growth was supported by robust global demand for AI-related hardware, semiconductors and automobiles, while imports reflected industrial restocking and higher commodity prices rather than a broad-based recovery in domestic consumption. Producer price inflation accelerated to 5% from 3.80% in August, its highest level since June 2022, while consumer inflation edged up to 0.90%, remaining below expectations and highlighting subdued domestic demand. Meanwhile, the offshore Yuan held near ¥6.69/$1, its strongest level since July 2022, as Beijing expanded offshore investment and financing channels to promote international use of the currency.
Next week, markets will focus on geopolitical tensions, oil-driven inflation risks, major earnings, and key global economic data, including China’s Q3 GDP and UK inflation.
GLOBAL MARKETS
US equities ended the week mixed but resilient, as a sharp technology-led selloff offset gains in more defensive and rate-sensitive sectors. Compared with the prior week, the S&P500 and Nasdaq decreased by 1.95% and 4.48% to close at 7,659.41 and 26,140.03 while the Dow Jones increased by 0.67% to close at 52,002.41.
European equities ended the week higher, with strong corporate earnings and a late-week easing in government bond yields helping offset earlier pressure from elevated energy prices and lingering fiscal concerns in France. Compared to last week, the German DAX, CAC 40 and FTSE100 increased by 2.13%, 1.97% and 3.13% to close at 25622.61, 7956.70, 10,881.90 respectively
Asian markets remained focused on growth prospects and the outlook for artificial-intelligence-related technology stocks, as a rebound late in the week helped markets recover from a broad semiconductor-led selloff. Compared to last week, the Hang Seng Index and TOPIX Index decreased by 0.10% and 0.95% to close at 24,186.83 and 4,066.10 respectively.
Next week, global markets will focus on upcoming US inflation and industrial production data, alongside Eurozone flash PMI estimates for France, Germany and the wider currency bloc, as well as China’s monthly economic activity, trade and credit figures.
DOMESTIC ECONOMY
Nigeria’s Inflation Eases to 14.63% in September, Extending Disinflation Trend for Fourth Consecutive Month
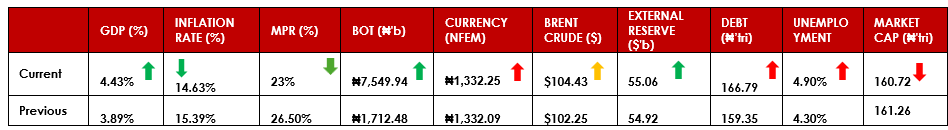
Nigeria’s headline inflation rate declined to 14.63% in September 2026 from 15.39% in August and 20.98% in September 2025, marking the fourth consecutive monthly decline. Month-on-month (M-o-M) headline inflation slowed to 0.06% from 0.71%, reflecting a moderation in price pressures. Food inflation fell to -1.55% from 1.02% in August, supported by lower prices of grains, rice, eggs, onions, palm oil and vegetables. However, core inflation accelerated to 1.11% from -0.06%, indicating persistent underlying price pressures. Urban inflation rose to 0.53% from 0.28%, while rural inflation declined to -0.89% from 1.79%. Meanwhile, the Naira strengthened to ₦1,333/$1 at the Nigerian Foreign Exchange Market on 14 October ahead of the inflation report. The continued decline in headline inflation signals easing price pressures, although rising core and urban inflation suggest that underlying inflationary risks remain.
Fitch Revises Credit Outlook to Positive, Affirms ‘B’ Rating
Fitch Ratings revised Nigeria’s credit outlook to Positive from Stable on 9 October 2026, while affirming its long-term issuer default rating at ‘B’, citing stronger foreign exchange reserves, ongoing economic reforms and moderating inflation. Gross foreign exchange reserves rose to $55.80billion as of October 2026, from $32billion in mid-April 2024, while the current account surplus is projected at 6.40% of GDP in 2026. Fitch forecasts GDP growth of 4.30% in 2026, up from 4% in 2025, and average annual inflation of 15.40%. Improved crude oil production, averaging 1.52 million barrels per day in Q2 2026, and increased domestic refining capacity are also expected to support external stability. However, fiscal pressures remain, with the budget deficit projected to widen to 3.60% of GDP in 2026 from 3.10% in 2025, while government interest payments are expected to average 27% of revenue between 2026 and 2028, compared with the 14% median for ‘B’ rated peers. The Positive outlook signals potential for a future upgrade if reforms, reserve accumulation and revenue mobilisation are sustained, although elevated debt-servicing costs, fiscal risks and external vulnerabilities remain key constraints.
LCCI Proposes Six-Month Programme to Reduce Petrol Prices by 15%–20%
The Lagos Chamber of Commerce and Industry (LCCI) proposed a six-month petrol price reduction programme targeting a 15–20% decline in pump prices to ease business operating costs and household expenses. The Chamber urged the Federal Government to collaborate with domestic refiners, petroleum marketers and regulators, while cautioning that the proposed price-stabilisation mechanism alone may not guarantee sustainable reductions. It also called for improved domestic refining efficiency, reliable electricity supply, expanded gas-to-power infrastructure and lower distribution costs. On monetary policy, the LCCI welcomed the Central Bank of Nigeria’s 350-basis-point reduction in the Monetary Policy Rate to 23%, but noted that high lending rates and tight credit conditions continue to constrain businesses, particularly MSMEs. Although inflation moderated in August, the Chamber warned that elevated petrol and diesel prices could reverse some of the progress by increasing transportation, production and distribution costs.
IMF Raises 2026 Growth Forecast to 4.20%, Urges Targeted Relief for Vulnerable Households
The International Monetary Fund (IMF) raised Nigeria’s 2026 GDP growth forecast by 0.10% to 4.20%, while maintaining its 2027 projection at 4.30%, citing improved macroeconomic stability and favourable terms of trade. However, the Fund warned that elevated food and energy prices could worsen poverty and food insecurity despite the improving growth outlook. It recommended temporary, targeted cash transfers and income support for vulnerable households, alongside stronger revenue mobilisation and fiscally sustainable spending. Nigeria’s real GDP grew by 4.43% year-on-year in Q2 2026, up from 4.23% in Q2 2025, while the World Bank projected 4.30% growth for 2026. Globally, the IMF expects growth to slow to 3.10% in 2026 before recovering to 3.40% in 2027, with headline inflation projected at 4.70% and 4.10%, respectively. The outlook highlights a divergence between improving macroeconomic indicators and persistent cost-of-living pressures, with targeted relief measures viewed as critical to supporting household welfare without undermining fiscal stability.
Next week, markets are expected to remain shaped by naira stability and crude oil prices, while investors monitor foreign exchange reserves and the impact of monetary easing amid persistent fiscal and cost-of-living pressures.
EUROBOND MARKET
Nigerian sovereign Eurobonds closed the week on a positive note, with the average yield declining by 33bps week on week to 7.12% from 7.45%, as buying interest was broad-based across the curve. Stronger demand was particularly evident in the mid curve. Sentiment was supported by easing geopolitical concerns following progress in ceasefire discussions involving the United States, Israel and Iran, alongside improved domestic credit sentiment after Fitch revised Nigeria’s sovereign outlook to positive.
Next week, Nigerian Eurobonds are expected to trade cautiously, with performance driven by movements in US Treasury yields, global interest-rate expectations, oil prices and emerging-market risk sentiment
ALTERNATIVE ASSETS
GOLD
Gold traded lower during the week, with spot gold closing at approximately $4,166.39/oz on 16 October, down 0.40% W-o-W, as elevated United States Treasury yields and expectations of a further Federal Reserve rate hike later in the year weighed on the non-yielding metal.
OIL
Brent crude gained 1.02% W-o-W to $105.89/bbl, while West Texas Intermediate (WTI) rose 3.78% W-o-W to $98.06/bbl, supported by Middle East supply risks, a larger-than-expected draw in United States crude inventories and tighter near-term supply conditions.
ETFs
Investor demand remained broadly risk-on, with global equity funds attracting inflows for a fourth consecutive week as Treasury yields eased toward the end of the period. However, money market funds recorded outflows of $46.73billion, reversing the prior week’s $153.98billion of net purchases, while investors ended a four-week buying streak in gold and other precious-metals funds with net sales of $1.14billion.
Next week, markets will focus on the Federal Reserve meeting minutes, United States inflation and activity data, Treasury-yield movements, Middle East supply developments and global fund-flow trends for direction across gold, oil and alternative assets.
MONEY MARKET AND FIXED INCOME
System liquidity strengthened during the week as inflows from approximately ₦2.41trillion in Open Market Operations (OMO) maturities outweighed the ₦188.22billion net debit from the Treasury-bill primary market auction. Average banking-system liquidity rose to a net long position of ₦5.83trillion from ₦4.02trillion in the prior week, while banks’ net placements at the CBN’s Standing Deposit Facility increased from about ₦3.86trillion on 13 October to ₦6.08trillion on 16 October. Funding conditions eased accordingly, with the Nigerian Overnight Financing Rate (NOFR) contracting by 47bps W-o-W to 20.40%.
Investor appetite remained concentrated in the 364-day Treasury bill, although the DMO adopted a more selective allotment approach at its 14 October auction. The CBN, on behalf of the DMO, raised ₦269.06billion from total subscriptions of about ₦1.03trillion, rejecting roughly 74% of bids; the 364-day bill attracted ₦982.21billion in subscriptions against a ₦350billion offer, with only ₦220billion allotted. The 364-day stop rate rose by 5bps to 15.90% its first increase since August while the 91-day and 182-day stop rates were unchanged at 15.50% and 15.80%, respectively.
In contrast, the FGN bond market maintained a bearish tone, with the average benchmark yield widening by 26bps W-o-W to 16.40% as investors repriced the curve ahead of the DMO’s ₦1.75trillion October bond auction.
Next week, money-market liquidity is expected to trade cautiously next week, with selective upside supported by improving liquidity, moderating inflation and Q3 earnings, while elevated fixed-income yields and profit-taking in banking stocks may limit gains.
EQUITIES MARKET
The Equities market closed bearish this week as the NGX All-Share Index and Market Capitalization depreciated by 0.33% to close the week at 247,539.73 and ₦160.72trillion respectively, compared to 248,363.55 and ₦161.26trillion last week
A total of 2.04million units valued at ₦447.27million were traded this week in 4,218 deals compared with a total of 1.83million units valued at ₦687.31million, transacted last week in 5,413 deals.
On a sectoral basis, major sectors also closed mixed, with the Consumer Goods, Oil & Gas and Industrial Goods index increasing by 0.09%, 3.13% and 04% while the Banking and Insurance indices closed negative decreasing by –3.15% and –0.14%.
Notable gainers this week were Livestock Feeds PLC and E-Transact International Plc while UPDC Real Estate Investment Trust and Nigerian Enamelware Plc. topped the losers list.
PRICE ADJUSTMENT
| S/N | Security | Ex-Div Date | Last Close Price | Dividend | Bonus | Ex-Div Price |
| 1 | PZ CUSSONS NIGERIA PLC | 12/10/2026 | ₦68.00 | ₦2.50 | NIL | ₦65.50 |
| 2 | GUARANTY TRUST HOLDING COMPANY PLC | 13/10/2026 | ₦131.00 | ₦1.00 | NIL | ₦130.00 |
| 3 | STANBIC IBTC HOLDINGS PLC | 16/10/2026 | ₦168.00 | ₦4.50 | NIL | ₦163.50 |
Next week, the NGX is expected to trade cautiously next week, with a selective upside bias supported by improving liquidity, moderating inflation and the Q3 earnings season, although profit-taking in banking stocks may limit gains.
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,764.45 | +0.36% |
| EUR/NGN | ₦1,490.08 | +0.23% |
| CAD/NGN | ₦937.96 | +1.23% |
| 16/10/2026 | 09/10/2026 | W-O-W % | |
| NAFEM | 1,332.25 | 1,332.09 | +0.02% |
| Parallel | 1,370 | 1,375 | -0.50% |
TOP GAINERS
| Ticker | Open | Close | Loss | % |
| LIVESTOCK | 13.15 | 19.00 | 5.85 | 44.49% |
| ETRANZACT | 12.10 | 17.30 | 5.20 | 42.98% |
| MULTITREX | 0.42 | 0.60 | 0.18 | 42.86% |
| AUSTINLAZ | 2.20 | 2.92 | 0.72 | 32.73% |
| OMATEK | 1.34 | 1.60 | 0.26 | 19.40% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| UPDCREIT | 24.00 | 21.15 | -2.85 | -11.88% |
| ENAMELWA | 40.70 | 36.65 | -4.05 | -9.95% |
| NASCON | 188.90 | 171.00 | -17.90 | -9.48% |
| TRANSEXPR | 2.97 | 2.70 | -0.27 | -9.09% |
| LIVINGTRUST | 3.20 | 2.93 | -0.27 | -8.44% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.