GLOBAL ECONOMY
The US S&P Global Composite PMI climbed to 58.40 from 56.00, marking the fastest expansion in private-sector activity in more than five years, while the Services PMI rose to 58.80, its strongest level since July 2021, driven by robust domestic demand, accelerating activity across technology, healthcare, industrials and consumer sectors. However, inflation concerns intensified as input costs rose at their sharpest pace since late 2022 and firms passed higher costs to consumers through increased selling prices. Trade data showed exports rising $4.50billion to $315.20billion, led by industrial supplies and capital goods, but imports surged $17.20billion to a record $420.80billion, widening the trade deficit to a 17-month high of $105.60billion from $92.80billion.
The Pound Sterling rebounded to £1/$1.324 as easing oil prices and stabilizing bond markets improved sentiment, though hawkish comments from Bank of England policymakers reinforced expectations of a rate hike in November. The UK S&P Global Composite PMI eased to 52.00 from 52.50 in August, a three-month low, as growth in both services (52.10) and manufacturing (51.90) moderated, while new business expansion softened and employment continued to decline. Inflationary pressures intensified, with private-sector input costs rising at the fastest pace since June due to higher energy, fuel and transport expenses, leading to stronger output price inflation. The construction sector remained under pressure despite improving to 46.10 from 44.30, as new orders fell at the fastest pace since June and job cuts accelerated amid project delays and supply chain disruptions.
The Euro recovered above €1/$1.12 after touching a 17-month low of $1.1161, though it remains down about 3% above the Dollar. The Eurozone S&P Global Composite PMI rose to 53.10 from 52.00, its highest level in nearly three-and-a-half years, while the Services PMI climbed to 53.00, the strongest reading since November 2025, supported by robust domestic demand and the fastest growth in new orders in 41 months. Euro Area producer prices surged 1.90% month-on-month and 8.20% year-on-year in August, the highest annual reading since February 2023, driven by a 5.60% increase in energy costs following a near 70% jump in European natural gas prices. While construction remained weak, the Eurozone Construction PMI improved slightly to 43.40, though activity continued to contract amid falling orders, rising costs and persistent weakness in residential building. Meanwhile, European Central Bank policymakers warned that inflation risks remain tilted to the upside despite delivering a rate hike that lifted the deposit rate to 2.50%, while stressing the need to keep future policy options open amid uncertainty linked to the US-Iran conflict and the Russia-Ukraine war.
The offshore Yuan strengthened to approximately ¥6.69/$1, supported by Beijing’s defense of its exchange-rate policy amid ongoing China-EU trade negotiations, where European officials highlighted a trade deficit exceeding €1billion ($1.12billion) per day. China’s foreign exchange reserves declined by $38.10billion month-on-month to $3.40trillion at the end of September 2026, largely due to the stronger US dollar and higher US Treasury yields impacting asset valuations, while the People’s Bank of China extended its gold-buying streak to 23 consecutive months, increasing holdings to 77.47 million fine troy ounces from 76.73 million ounces.
Next week, markets will focus on the US-Iran conflict, U.S. inflation data, key economic releases from Europe and China, and major corporate earnings for direction.
GLOBAL MARKETS
US equities ended mixed but resilient as easing labour market concerns helped offset pressure from higher Treasury yields and oil prices. Focus now shifts to upcoming inflation, retail sales and industrial production data for clues on the Federal Reserve’s policy path. Compared with the prior week, the Dow Jones Index, S&P 500 and Nasdaq increased by 0.93%, 1.15% and 0.64% to close at 51,654.95, 7,811.54 and 27,366.17 respectively.
European equities ended the week mixed as higher sovereign bond yields, elevated energy prices and renewed concerns over fiscal sustainability, particularly in France, weighed on risk appetite despite a late-week rebound. Compared to last week, the German DAX and CAC 40 decreased by 0.57% and 1.19% to close at 25,087.27 and 7,803.33 respectively while the FTSE 100 increased by 0.86% to close at 10,552.05.
Asian markets remained focused on growth prospects as strong trade performance and accommodative liquidity conditions provided support despite ongoing global trade tensions. Compared to last week, the Hang Seng Index and TOPIX Index increased by 1% and 0.34% to close at 24,211.35 and 4,104.81 respectively.
Next week, global markets will focus on upcoming US inflation, retail sales and industrial production data, alongside Eurozone industrial and trade releases and China’s trade and credit figures, as investors assess the impact of easing labour-market conditions, elevated bond yields and energy prices on the global growth and interest-rate outlook.
DOMESTIC ECONOMY
World Bank Raises Nigeria’s Growth Forecast to 4.30% as Reforms, Investment Recovery Boost Economic Outlook
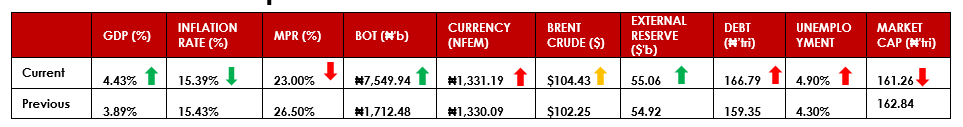
The World Bank has upgraded Nigeria’s economic growth forecast to 4.30% in 2026 from 4% in 2025, with growth expected to strengthen further to 4.40% annually in 2027 and 2028, citing improving macroeconomic stability, rising investor confidence and a gradual recovery in private sector investment. The upgrade places Nigeria among top African economies benefiting from ongoing reforms, alongside Zambia, Ethiopia and Angola, while the World Bank also raised Sub-Saharan Africa’s 2026 growth forecast to 4.30% from 4.10%. Supporting the optimistic outlook, Nigeria’s real Gross Domestic Product (GDP) expanded by 4.43% year-on-year in the second quarter of 2026, up from 4.23% a year earlier, extending the growth momentum from the 4.07% recorded in the fourth quarter of 2025. The improved outlook comes despite global headwinds, including higher energy prices and supply chain disruptions, and follows Standard & Poor’s (S&P) Global Ratings’ upgrade of Nigeria’s sovereign credit rating to B from B-, reinforcing positive sentiment around the country’s economic reforms and medium-term growth prospects.
Nigeria’s Net Foreign Reserves Surge to Record $46Billion as Foreign Exchange Stability Boosts Investor Confidence
Nigeria’s external position strengthened significantly after Central Bank of Nigeria (CBN) Governor Olayemi Cardoso disclosed that net foreign reserves climbed to a record $46billion, while gross reserves reached an all-time high of $55billion, exceeding the Central Bank’s earlier 2026 projection of $51.04billion. The latest net reserve position represents an increase of $11.20billion from $34.80billion at the end of 2025 and marks a dramatic recovery from levels below $1billion during the peak of the foreign exchange crisis. Investor confidence has been further supported by improving foreign exchange market stability, with the naira trading within a narrow range of ₦1,330.50/$1 to ₦1,332.99/$1 and closing at ₦1,332.75/$1 on October 7, while turnover at the Nigerian Foreign Exchange Market (NFEM) surpassed $1.01billion. The stronger reserve buffer, stable foreign exchange market and improving macroeconomic outlook, including the World Bank’s upgraded 2026 growth forecast of 4.30%, underscore growing confidence in Nigeria’s economic reforms and ability to attract and retain foreign capital.
Nigerian States’ Revenues Surge 93% as Capital Spending Rises to 61% of Budgets Amid Reform Windfall
Nigerian state governments recorded a 93% increase in real revenues between 2023 and 2025, while expenditures rose 92%, according to the World Bank, reflecting the fiscal benefits of foreign exchange reforms, petrol subsidy removal and improved revenue administration. As revenues expanded, states increased their focus on infrastructure, with capital expenditure rising from 46% to 61% of total spending, led by investments in transport, housing and agriculture. While spending on health, education and social protection also increased, education’s share of total expenditure declined from 14.90% in 2021 to 12.10% in 2025, health spending remained around 7%, and social protection increased from 1.40% to 4.40%. The report highlighted an improving macroeconomic backdrop, with Nigeria’s real Gross Domestic Product (GDP) growth accelerating to 4.20% in the first half of 2026 from 3.90% a year earlier, while the current account surplus improved to $12billion or 7.10% of GDP and gross external reserves exceeded $54billion. The World Bank noted that the sharp rise in state revenues presents a unique opportunity to improve infrastructure and public services, but stressed that stronger spending efficiency, accountability and service delivery will be critical to translating higher revenues into better living standards and sustainable economic growth.
Next week, markets will closely monitor the inflation report from the National Bureau of Statistics (NBS). However, risks from global inflationary pressures, elevated energy prices, tighter financial conditions, geopolitical tensions, and rising debt-servicing costs remain key headwinds to the country’s economic outlook.
EUROBOND MARKET
Nigerian sovereign Eurobonds closed the week on a weaker note, with the average yield rising by 25bps W-o-W to 7.79% from 7.54%, reflecting broad-based selling pressure across the curve. Long-dated maturities led the decline, as yields on the 2051, 2049, and 2046 bonds increased to 8.76%, 8.61%, and 8.64%, respectively. Market sentiment was pressured by the global bond sell-off, with higher United States Treasury yields and persistent inflation concerns weighing on demand for emerging-market debt.
Nigerian Eurobonds may remain sensitive to movements in United States Treasury yields, global interest rate expectations, oil prices, and broader emerging-market risk sentiment in the coming week.
ALTERNATIVE ASSETS
GOLD
Gold rebounded during the week but remained under pressure from elevated United States Treasury yields and expectations that the Federal Reserve could maintain a restrictive policy stance. Spot gold closed at approximately $4,193.87/oz, recovering from a two-month low as the United States Dollar weakened and oil prices eased toward the end of the week. Markets were supported by cooling inflation expectations and a reduced probability of an October Federal Reserve rate hike, although higher real yields continued to cap gains.
OIL
Brent crude gained 2.13% W-o-W to $104.43/bbl, while West Texas Intermediate (WTI) rose 0.60% to $91.66/bbl, supported by Middle East supply risks and shipping disruptions despite efforts to ease global fuel shortages.
ETFs
Investor demand remained strong, with United States-listed ETFs recording $17.50billion in net inflows, led by the Vanguard S&P 500 ETF ($4.45billion) and Invesco QQQ Trust ($3.13billion). Globally, money market funds attracted $153.81billion, bond funds received $26.03billion, and gold funds gained $1.41billion, reflecting a preference for defensive assets amid rising yields.
Next week, Markets will focus on Federal Reserve meeting minutes, United States Treasury yields, inflation data, Middle East developments and fund-flow trends for direction across Gold, Oil and alternative assets.
MONEY MARKET AND FIXED INCOME
System liquidity remained elevated but trended lower during the week as the Central Bank of Nigeria OMO Auction sterilised a substantial portion of excess market liquidity. Opening liquidity declined from about ₦4.93trillion to ₦3.70trillion by week-end following net OMO and Treasury bill settlements, although funding conditions remained comfortable, with the Nigerian Overnight Financing Rate (NOFR) largely stable at 20.00% and system balances comfortably in positive territory throughout the period.
Investor appetite for short-term instruments remained strong, evidenced by robust subscriptions at both OMO and NTB auctions. The CBN allotted ₦3.31trillion at its OMO auction against subscriptions of ₦3.51trillion, while the Debt Management Office allotted ₦968.47billion at the NTB auction from total subscriptions of ₦1.77trillion. The 364-day NTB stop rate eased marginally to 15.85% from 15.89%, reflecting sustained demand for short-dated fixed-income assets.
The Treasury bills and OMO secondary markets traded with mixed sentiments. While OMO yields remained under upward pressure due to increased supply from recent auctions, selective demand emerged across the April, June, November and December maturities. Meanwhile, activity in the NTB market was relatively subdued, although demand for the newly issued one-year bill supported yields around the 15.70%-15.90% range.
The FGN bond market maintained a broadly bearish tone, as persistent profit-taking by domestic investors outweighed sporadic offshore demand. Mid-curve benchmark yields gradually climbed during the week, with the FGN 2038 bond rising from around 16.50% to 16.75%, while average benchmark yields moved closer to the 16.50%-17.00% range. Nonetheless, buying interest improved towards the end of the week, particularly across the short- and mid-segments of the curve, suggesting investors are beginning to see value at current yield levels.
Next week, money-market liquidity is expected to remain strong with possible CBN liquidity-management actions, as investor focus centre on potential OMO auctions, NTB market activity and the release of the fourth-quarter borrowing calendar.
DOMESTIC MARKETS
Nigerian Government Securities Dominate Capital Market Listings as ₦11.08trillion Accounts for 80% of Nigerian Exchange Activity
Government securities accounted for ₦11.08trillion, or 80%, of the ₦13.86trillion in identifiable new and supplementary listings on the Nigerian Exchange (NGX) during the first nine months of 2026, underscoring the Federal Government’s continued reliance on the domestic debt market to fund its financing needs. Federal Government of Nigeria (FGN) instruments alone contributed ₦10.54trillion, while the FGN Roads Sukuk added ₦300billion and Lagos State bonds contributed ₦244.82billion. Major listings included the 15.45% FGN June 2038 bond, which recorded multiple reopenings totaling over ₦2.44trillion, alongside ₦1.37trillion of the 17.95% FGN June 2032 bond, ₦888.63billion of the 16.79% FGN September 2036 bond and ₦817.07billion of the 19% FGN February 2034 bond. The dominance of sovereign debt reflects elevated government borrowing requirements, with Nigeria’s 2026 budget carrying a ₦23.85trillion deficit and the Federal Government increasing its borrowing plan to ₦29.20trillion after the fiscal deficit widened to ₦31.46trillion, further cementing government securities as the primary driver of capital market activity while corporate and other non-government issuances accounted for just ₦2.78trillion.
EQUITIES MARKET
The Equities market closed bearish this week as the NGX All-Share Index and Market Capitalization depreciated by 0.97% to close the week at 248,363.55 and ₦161.26trillion respectively, compared to 250,808.27 and ₦162.84trillion last week
A total turnover of 2.72 billion shares worth ₦158.28billion in 209,986 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 3.17billion shares valued at ₦155.02billion that exchanged hands last week in 206,662 deals.
On a sectoral basis, major sectors also closed negatively, with the Banking, Consumer Goods, Oil & Gas and Insurance indices decreasing by -2.64%, -0.58%, -3.85% and -1.74 while the Industrial Goods index closed positive increasing by 0.02%.
Notable gainers this week were Livestock Feeds PLC and Tripple Gee and Company PLC while Critical Minerals Financing PLC and ABC Transport PLC topped the losers list.
SUPPLEMENTARY LISTINGS
Guinea Insurance Raises ₦9.18bn Through Private Placement, Expands Share Capital by 56.57%
Guinea Insurance Plc has listed an additional 6.31billion ordinary shares on the Nigerian Exchange (NGX), following the completion of its private placement of 6.33bn ordinary shares at ₦1.45 per share, raising approximately ₦9.18billion. As a result, the company’s total issued and fully paid-up share capital increased by 56.57% from 11.15billion shares to 17.46billion shares. The additional shares were officially admitted to the Daily Official List of NGX on 7 October 2026, strengthening the insurer’s capital base and supporting its strategic growth objectives.
SHARE CAPITAL RECONSTRUCTION
Sterling Financial Holdings Company Plc: Implementing the Share Capital Reconstruction
Sterling Financial Holdings Company Plc has successfully completed its share capital reconstruction, reducing its issued shares by a 10-for-1 ratio from 68.50billion ordinary shares to 6.85billion ordinary shares of ₦0.50 each. Following the exercise, the old shares were delisted and the reconstructed shares were listed on the Nigerian Exchange (NGX) on 8 October 2026 at ₦77 per share. The reconstruction was approved by shareholders at the company’s 6 June 2026 Annual General Meeting and received regulatory clearance from the Securities and Exchange Commission (SEC). Consequently, NGX has lifted the trading suspension previously placed on the company’s shares, allowing normal trading to resume.
Next week, the NGX is expected to remain driven by selective buying in fundamentally strong stocks, amid subdued sentiment, profit-taking and stock-specific positioning.
CURRENCY
| (₦/$) | 09/10/2026 | 02/10/2026 | W-O-W% |
| NAFEM | 1,331.19 | 1,330.09 | 0.08% |
| Parallel | 1,364.00 | 1,375.00 | -0.80% |
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,800.67 | +1.41% |
| EUR/NGN | ₦1,523.37 | +0.94% |
| CAD/NGN | ₦953.92 | +1.36% |
TOP GAINER
| Ticker | Open | Close | Loss | % |
| LIVESTOCK | 8.90 | 13.15 | 4.25 | 47.75% |
| TRIPPLEG | 2.33 | 3.09 | 0.76 | 32.62% |
| GUINEAINS | 0.72 | 0.93 | 0.21 | 29.17% |
| LEARNAFRCA | 7.65 | 9.15 | 1.50 | 19.61% |
| MULTITREX | 0.36 | 0.42 | 0.06 | 16.67% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| CMFC | 4.49 | 3.58 | -0.91 | -20.27% |
| ABCTRANS | 7.40 | 6.05 | -1.35 | -18.24% |
| JAPAULGOLD | 2.88 | 2.56 | -0.32 | -11.11% |
| FIDELITYBK | 23.50 | 21.00 | -2.50 | -10.64% |
| ARADEL | 1530.00 | 1377.00 | -153.00 | -10.00% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.