GLOBAL ECONOMY
US crude inventories posted a larger-than-expected drawdown of between 3.06 million and 4.93 million barrels, significantly exceeding forecasts, while gasoline stocks fell by up to 2.95 million barrels, signaling firm fuel demand. Meanwhile, the US labour market remained resilient as initial jobless claims declined by 6,000 to 194,000, the lowest level since July, while continuing claims rose to 1.73 million. Business activity remained robust, with the S&P Global Manufacturing PMI rising to 56.00, its strongest level since May 2022, and the Services PMI remaining elevated at 57.90, supported by firm domestic demand and accelerating export orders. Despite this, inflation concerns intensified, with the one-year inflation expectation increasing to 4.70% and the five-year outlook rising to 3.50%, while consumer sentiment improved slightly to 48.00 but remained near five-month lows.
The British Pound held near a one-month high at just below £1/$1.34, supported by stronger-than-expected business activity as flash PMI data showed private-sector growth accelerated. Labour market conditions also remained resilient, with the unemployment rate falling to 4.70% from 4.90%, employment increasing by 102,000.00 to 34.58 million, and payrolled employees rising by 13,000.00 to 30.30 million. Wage growth remained firm, with regular pay excluding bonuses rising 3.70% YoY to £707.00 per week and total earnings increasing 3.70% to £757 per week. However, inflationary pressures intensified, with headline inflation accelerating to 3.50% in September, its highest level in eleven months, while core inflation rose to 2.80%, a six-month high, driven by higher transport, energy and services costs.
The Euro remained near multi-month lows around €1/$1.12 amid concerns over slowing growth, fiscal pressures and rising sovereign borrowing costs, particularly in France. The Eurozone current account surplus narrowed sharply to €7.70billion from €18.10billion a year earlier, with the goods surplus falling to €10.50billion, the lowest since April 2023, while the cumulative surplus for the first eight months of 2026 declined to €130.20billion from €148.20billion. The Eurozone Composite PMI fell to 51.90 from 53.10, with the Services PMI declining to 51.70 and the Manufacturing PMI easing to 52.40, reflecting softer demand, weakening new orders and near-stagnant hiring. Inflation expectations also increased, with consumers expecting prices to rise 3.10% over the next 12 months, the highest in four months, while unemployment expectations rose to 11.30% and economic growth expectations deteriorated to -1.50%.
The offshore Yuan remained near a four-year high at approximately ¥6.67/$1 as China’s economy expanded 4.50% YoY in Q3 2026, beating expectations of 4.40% and accelerating from 4.30% in Q2, while quarterly growth improved to 1.20% from 0.90%, keeping the full-year growth target of 4.50%-5.00% within reach. Growth was supported by resilient exports, particularly AI-related and high-tech products, with September exports surging 36.30% YoY to $447.18 billion, while industrial production accelerated to a six-month high of 5.50% and retail sales rose 1.10%, also the strongest pace in six months. Labour market conditions improved modestly, with the urban unemployment rate easing to 5.20% from 5.30%, while youth unemployment declined to 18.00% from 18.90%. The People’s Bank of China (PBOC) maintained the 1-year Loan Prime Rate (LPR) at 3.00% and the 5-year LPR at 3.50% for a seventeenth consecutive month, reflecting reduced urgency for broad monetary easing following stronger growth data. Despite the improving macroeconomic backdrop, foreign direct investment (FDI) declined 4.30% YoY to ¥548.80 billion ($82.20 billion) in the first nine months of 2026, fixed-asset investment contracted 7.20%, and property investment plunged 20.60%.
Next week, markets will focus on geopolitical tensions, oil-driven inflation risks, major earnings, and key global economic data, including China’s Q3 GDP and UK inflation.
GLOBAL MARKETS
US equities closed the week mixed as concerns over rising AI infrastructure spending costs, higher Treasury yields and surging oil prices weighed on technology stocks. Energy shares outperformed on stronger crude prices. Compared with the prior week, the S&P500 and Nasdaq decreased by 0.47% and 0.71% to close at 7,623.68 and 25,955.34 while the Dow Jones increased by 0.41% to close at 52,215.16.
European equities ended the week lower as elevated energy prices, slowing economic activity and concerns over fiscal pressures across the region weighed on sentiment. While corporate earnings provided some support, weak economic data, softer business confidence and rising sovereign borrowing costs, particularly in France, kept investors cautious. Compared to last week, the German DAX, CAC 40 and FTSE100 decreased by 1.72%, 2.19% and 1.76% to close at 25,181.65, 7,782.82 and 10,690.36 respectively.
Asian equities ended the week lower as concerns over global growth, elevated energy prices and volatility in artificial-intelligence-related technology stocks weighed on sentiment. Although a late-week rebound supported markets following a semiconductor-led selloff. Compared to last week, the Hang Seng Index and TOPIX Index decreased by 4.52% and 2.46% to close at 23,093.37 and 3,965.81 respectively.
Next week, investors will focus on the Federal Reserve’s rate decision, key inflation data and corporate earnings, while monitoring China’s growth outlook, Eurozone economic activity and geopolitical developments for clues on the direction of global markets.
DOMESTIC ECONOMY
Nigeria’s Money Supply Hits ₦146.60trillion as CBN Bills Surge 57,744.00%, Drive Liquidity Expansion
Nigeria’s broad money supply (M3) increased by 5.40% month-on-month to ₦146.60trillion in September 2026 from ₦139.09trillion in August, driven predominantly by a sharp rise in Central Bank of Nigeria (CBN) bills, which surged from ₦9.68billion to ₦5.60trillion and accounted for 74.40% of the ₦7.51trillion increase in money supply. While the narrower money supply measure (M2) grew by a modest 1.38% to ₦141trillion, credit to the government rose 19.26% month-on-month to ₦39.40trillion and 63.09% year-on-year, contrasting with a 0.64% decline in private-sector credit to ₦83.93trillion. Net domestic credit expanded 4.96% to ₦123.34trillion, while net foreign assets fell 13.57% to ₦30.90trillion, highlighting a growing reliance on domestic assets. The liquidity shift comes as the CBN intensified Open Market Operations (OMO), selling ₦17.51trillion of bills against ₦10.89trillion in maturities, resulting in a net ₦6.62trillion liquidity withdrawal, even as the Monetary Policy Rate (MPR) was reduced by 350 basis points to 23%, signaling an evolving monetary policy stance aimed at balancing inflation control and economic growth.
Government Borrowing Surges 63.09% as Private Sector Credit Contracts Amid Tight Financing Conditions
Credit to the Nigerian government climbed by 63.09% year-on-year to ₦39.40trillion in September 2026 from ₦24.16trillion a year earlier, with a sharp monthly increase of 19.26% (₦6.36trillion) from ₦33.04trillion in August, making government financing the largest driver of domestic credit growth. Net domestic credit rose by 4.96% month-on-month to ₦123.34trillion, while credit to the private sector declined by 0.64% to ₦83.93trillion, a reduction of ₦537.61billion from August, despite remaining 15.73% higher year-on-year. Over the past year, government borrowing accounted for 57.20% of the ₦26.65trillion increase in net domestic credit, compared with 42.80% from private-sector lending. The trend highlights a growing shift of financial system liquidity toward public-sector financing, even as businesses contend with tighter credit conditions.
FAAC Distributes ₦2.43Trillion as Federal Government Receives ₦832.24Billion Amid Higher Statutory Revenue
The Federation Account Allocation Committee (FAAC) distributed ₦2.43trillion to the Federal Government, 36 state governments and 774 local government councils for September 2026, supported by higher statutory revenue collections. Total gross revenue available for distribution rose to ₦3.91trillion, with statutory revenue increasing by ₦246.38billion to ₦3.10 rillion, while Value Added Tax (VAT) collections declined by ₦17.97billion to ₦816.87billion. Of the distributable revenue, the Federal Government received ₦832.24billion, states received ₦799.87billion, local governments got ₦560.66billion, while oil-producing states shared ₦236.05billion as 13% derivation revenue. The revenue growth was driven by stronger Petroleum Profit Tax, Hydrocarbon Tax, petroleum royalties, import duties and excise duties, underscoring continued resilience in federally collected revenues despite weaker VAT receipts and declines in Companies Income Tax and other non-oil revenue sources.
FG Targets 7% Economic Growth, Rejects IMF’s 4.30% Forecast as Reforms Drive Investment Push
Nigeria is targeting 7% economic growth, significantly above the International Monetary Fund (IMF) projection of 4.30% for 2027, as the Federal Government intensifies reforms aimed at lowering inflation, reducing borrowing costs and boosting investment. Finance Minister Taiwo Oyedele stated that the IMF’s forecasts are overly conservative, expressing confidence that ongoing fiscal, foreign exchange and tax reforms will accelerate growth beyond current expectations. The government is focusing on tackling food, energy and logistics costs to curb inflation and create conditions for single-digit interest rates, a move expected to ease business financing costs that currently approach 30%. While the IMF recently raised Nigeria’s 2026 growth forecast to 4.20% and maintained its 4.30% outlook for 2027, the government believes sustained reforms, foreign exchange stability and improved investor confidence could deliver stronger expansion. Oyedele also warned that reversing key reforms, particularly fuel subsidy removal, could trigger capital flight, weaken the naira and undermine economic stability, reinforcing the administration’s commitment to maintaining its reform agenda.
Nigeria Chairs UN Budget Committee for First Time in 66 Years as Tinubu Receives Proposed $14Billion UN Budget
President Bola Tinubu has received the United Nations’ proposed 2027 budget, marking a historic milestone as Nigeria chairs the United Nations General Assembly’s Fifth Committee on Administrative and Budgetary Matters for the first time in 66 years. The proposed budget, presented by Nigeria’s Permanent Representative to the United Nations, Ambassador Jimoh Ibrahim, includes a regular budget of $3.40billion and a peacekeeping budget of $8.50billion, with the combined envelope estimated at approximately $14billion (about ₦36trillion to ₦40trillion). Nigeria assumed the chairmanship of the committee on September 3, 2026, placing the country at the center of global deliberations on the United Nations’ finances, governance and resource allocation. While the budget remains subject to negotiations and approval by member states, the development strengthens Nigeria’s influence within the multilateral system at a time of ongoing debates over United Nations reforms, African representation on the Security Council and funding challenges facing global humanitarian operations.
NEC Approves 90-Day Cost-of-Living Plan, Targets Lower Food Prices and Single-Digit Inflation by 2027
The National Economic Council (NEC) has approved a 90-day economic action plan aimed at easing Nigeria’s cost-of-living crisis, improving food affordability, removing investment bottlenecks and accelerating high-impact projects with direct benefits to households and businesses. The plan prioritizes five key areas: food affordability, tax harmonisation, completion of critical projects, investment facilitation and targeted household support, while a new national dashboard will track project execution and the use of fuel subsidy savings. Vice President Kashim Shettima and Finance Minister Taiwo Oyedele emphasized translating recent macroeconomic gains into tangible improvements for Nigerians, with the government targeting single-digit inflation and interest rates by 2027. NEC also approved a joint Federal Government-state financing framework to accelerate the rollout of Compressed Natural Gas (CNG) and electric vehicles, with authorities directed to ensure cost savings are reflected in lower transport fares. The initiative forms part of broader efforts to cushion the impact of economic reforms, amid continued high transport costs and petrol prices ranging between ₦1,370 and ₦1,400 per litre.
Next week, investors will closely monitor inflation trends, foreign exchange stability, crude oil price movements, external reserves and fiscal reform implementation, as investors assess their implications for economic growth, investor confidence and overall market sentiment.
EUROBOND MARKET
The Nigerian sovereign Eurobond market closed the week on a weaker note, with the average yield rising by 2bps week-on-week to 7.40%, reflecting mild selling pressure and softer demand for dollar-denominated securities. Market activity remained subdued across the curve as investors adopted a cautious stance amid evolving global macroeconomic conditions and uncertainty around the interest-rate outlook. The uptick in yields indicates a slight deterioration in market sentiment, with investors demanding higher risk premiums to hold sovereign debt.
Next week, Nigerian Eurobonds are expected to trade cautiously, with performance likely to be influenced by investor appetite for emerging-market assets, movements in United States Treasury yields, global interest-rate expectations and broader risk sentiment across international fixed-income markets.
ALTERNATIVE ASSETS
GOLD
Gold came under sustained pressure during the week ended 23 October 2026, with spot prices falling below the key $4,000.00/oz psychological level and closing around $3,994.00/oz, down approximately 4.10% W-o-W. The decline was driven by higher United States Treasury yields, stronger inflation expectations following rising energy prices, and markets pricing a high probability of an additional Federal Reserve rate hike in December.
OIL
Crude oil rallied sharply during the week, supported by escalating Middle East geopolitical risks, tightening global supply conditions and larger-than-expected draws in United States crude inventories. Brent crude gained approximately 6.20% W-o-W to settle near $116.72/bbl, while supply disruption concerns continued to underpin bullish sentiment across energy markets.
ETFs
Investor sentiment remained broadly constructive toward risk assets as global equity funds continued to attract inflows amid expectations that the Federal Reserve may hold rates steady at its October meeting. However, precious metals exchange-traded funds (ETFs) experienced renewed selling pressure following gold’s break below $4,000.00/oz, while elevated oil prices and inflation concerns prompted investors to rebalance portfolios toward energy-linked and defensive sectors
Next week, markets will focus on the Federal Reserve policy meeting, United States Personal Consumption Expenditures (PCE) inflation data, Treasury yield movements, geopolitical developments in the Middle East and global fund-flow trends. Gold may remain under pressure if rate-hike expectations strengthen further, while oil prices are likely to remain sensitive to supply disruptions and geopolitical risks across major producing regions.
MONEY MARKET AND FIXED INCOME
System liquidity remained robust during the week, supported by approximately ₦3.67trillion in Open Market Operations (OMO) maturities, ₦2.07trillion in OMO repayments and Federation Account Allocation Committee (FAAC) inflows. Liquidity peaked at ₦9.04trillion before moderating to ₦6.94trillion following the settlement of the Central Bank of Nigeria (CBN)’s ₦2.63trillion OMO auction and the Debt Management Office (DMO)’s bond auction. Consequently, funding conditions remained stable, with the Nigerian Overnight Financing Rate (NOFR) anchored at the 20.00% Standing Deposit Facility (SDF) floor throughout the week.
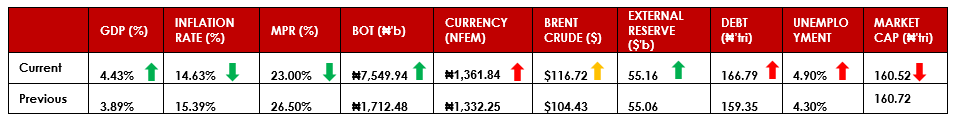
In the Treasury-bills market, sentiment remained mildly bullish as the softer September inflation print of 14.63% YoY and elevated liquidity supported demand. The CBN offered ₦2.00trillion across 138-day and 180-day OMO bills, attracting ₦2.73trillion in subscriptions and allotting ₦2.63trillion. Stop rates settled at 17.63% and 17.14%, respectively. Meanwhile, the newly issued 364-day Nigerian Treasury Bill (NTB) traded below its auction stop rate, closing around 15.60% – 15.75%.
The Federal Government of Nigeria (FGN) bond market traded with mixed sentiment. Initial bearishness followed the DMO’s ₦5.75trillion fourth-quarter borrowing programme, but sentiment improved after the lower-than-expected inflation reading and strong demand at the October bond auction. The DMO allotted ₦2.01trillion, comprising ₦1.21trillion in competitive bids and ₦800.00billion in non-competitive allotments. Stop rates cleared at 16.99% for the 19.00% FGN February 2034, 17.29% for the 16.79% FGN September 2036, and 17.19% for the 15.45% FGN June 2038, while secondary-market yields compressed across key mid-tenors.
Next week, money-market liquidity is expected to remain comfortable, although OMO auctions and Cash Reserve Requirement (CRR) debits could moderate surplus funds. In fixed income, ample liquidity and easing inflation should support sentiment, while elevated OMO yields and increased government borrowing may limit further yield declines.
EQUITIES MARKET
The Equities market closed bearish this week as the NGX All-Share Index and Market Capitalization depreciated by 0.13% to close the week at 247,222.27 and ₦160.52trillion compared to 247,539.73 and ₦160.72trillion last week.
A total of 2.02 billion shares worth ₦110.77billion in 173,113 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 1.66 billion shares valued at ₦98.09billion that exchanged hands last week in 184,632 deals.
On a sectoral basis, major sectors closed negatively, with the Consumer Goods, Oil & Gas, Banking and Insurance indices decreasing by -0.55%,-2.55%, -0.67% and -2.79% while only the Industrial Goods index closed positive increasing by 1.95%,
This week, notable gainers were ABC Transport PLC and AVA Capital PLc while UPDC Real Estate Investment Trust PLC and Omatek Ventures PLC topped the losers list.
Going forward, market sentiment is expected to remain cautious and selective, with investors focusing on earnings prospects, valuations and dividend potential. However, ongoing price corrections may create bargain-hunting opportunities in fundamentally strong stocks, supporting a market rebound if buying interest improves.
CURRENCY
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,822.28 | +0.67% |
| EUR/NGN | ₦1,525.80 | -0.04% |
| CAD/NGN | ₦974.08 | +1.40% |
| 16/10/2026 | 09/10/2026 | W-O-W % | |
| NAFEM | 1,361.84 | 1,332.25 | 2.22% |
| Parallel | 1,390.00 | 1,370.00 | 1.46% |
TOP GAINERS
| Ticker | Open | Close | Loss | % |
| ABCTRANS | 6.05 | 7.30 | 1.25 | 20.66% |
| AVACAP | 6.20 | 7.30 | 1.10 | 17.74% |
| CAVERTON | 4.10 | 4.80 | 0.70 | 17.07% |
| FIDELITYBK | 21.05 | 24.00 | 2.95 | 14.01% |
| MULTITREX | 0.60 | 0.66 | 0.06 | 10.00% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| UPDCREIT | 21.15 | 17.50 | -3.65 | -17.26% |
| OMATEK | 1.60 | 1.40 | -0.20 | -12.50% |
| UPL | 4.95 | 4.35 | -0.60 | -12.12% |
| REGALINS | 0.80 | 0.71 | -0.09 | -11.25% |
| NGXGROUP | 170.00 | 152.50 | -17.50 | -10.29% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.