GLOBAL ECONOMY
The US economy presented mixed signals, with Q2 GDP growth revised upward to 2.20% annualised from 1.50%, although still below Q1’s 2.50%. Inflation remained above the Fed’s 2.00% target, with headline and core Personal Consumption Expenditures (PCE) inflation at 3.40% and 3.00% Year-on-Year, respectively. Labour-market conditions weakened in September, as payroll growth slowed sharply to 29,000 from 133,000 in August, while unemployment edged up to 4.20% from 4.10% and annual wage growth moderated to 3.00% from 3.10%. Consumer spending remained firm, with August nominal and real spending rising 0.90% and 0.60% Month-on-Month , respectively. Meanwhile, the September Institute for Supply Management Purchasing Managers’ Index (ISM PMI) remained in expansion at 54.50, marginally below 54.60 in August, while the prices-paid index increased sharply to 77.90 from 71.10, indicating renewed cost pressures. The August trade deficit also widened to $132.60billion from $118.90billion, pointing to continued external imbalances.
The UK economy maintained modest activity momentum although inflationary and borrowing-cost pressures persisted. In September 2026, manufacturing PMI edged up to 51.90 from 51.70 in August, marking an 11th month of expansion, while shop-price inflation eased to 1.40% Y-o-Y from 1.50%. Housing remained subdued, with Nationwide house-price growth slowing to 0.80% Y-o-Y in September from 1.60% in August, while prices fell 0.20% M-o-M following a 0.20% increase. Meanwhile, Q2 GDP growth was revised up to 0.50% Quarter-on Quarter from 0.40%, following 0.60% in Q1, while annual growth accelerated to 1.40% from 0.80%. In August 2026, net mortgage borrowing rose to £4.40billion from £4.10billion, but mortgage approvals fell to 54,900 from 55,900, indicating continued pressure from borrowing costs. The 10-year gilt yields also remained elevated near 5.40% after rising 23bps in September, as higher energy prices intensified inflation concerns and expectations for tighter Bank of England (BoE) policy.
The Eurozone economy showed stronger manufacturing activity but renewed inflation pressure. September 2026 inflation accelerated to 3.80% Y-o-Y from 3.20% in August, above the 3.60% expectation and the European Central Bank’s (ECB’s) 2.00% target, driven largely by energy inflation, which surged to 18.80% from 6.30%. Core inflation also edged up to 2.50% from 2.40%. Meanwhile, September manufacturing PMI rose to 52.90 from 51.20 in August, its strongest since May 2022, while August unemployment held at 6.40%, unchanged from July but above 6.30% a year earlier. Economic sentiment weakened in September, with the indicator falling to 97.90 from 98.40 in August, while consumer confidence declined to -16.50 from -15.50, reflecting rising energy costs. The stronger inflation backdrop increased pressure on the ECB to tighten policy, although weak growth and the energy shock are likely to keep its approach cautious.
China’s economy showed signs of improved activity as persistent domestic demand weakness continued to drive expectations for further policy support. The official manufacturing PMI returned to expansion at 50.10 from 49.80 in August, services activity also improved, with the official non-manufacturing PMI rising to 50.20 from 49.00. The National Bureau of Statistics (NBS) Composite PMI increased to 50.70 from 49.50, marking a return to overall expansion. However, earlier August 2026 data showed retail sales growth slowing to 0.40% Y-o-Y, while fixed-asset investment contracted 7.20% in the first eight months, highlighting weak domestic demand. The Q2 2026 current-account surplus widened to ¥193.70billion from ¥184.30billion in Q1, supported by a larger goods and services surplus. Meanwhile, China’s latest stimulus measures, including mortgage subsidies and expanded central bank funding, have yet to fully address concerns over domestic demand.
Next week, markets will focus on the US-Iran standoff and developments around the Strait of Hormuz, US FOMC minutes, Eurozone PPI, ECB meeting and inflation, employment and trade data across major economies.
GLOBAL MARKETS
US equities ended the week mixed, as investors navigated a global bond sell-off, elevated Treasury yields and higher oil prices before a weaker-than-expected September US jobs report supported a late-week recovery. Compared with the prior week, the Dow Jones Index and S&P 500 Index decreased by 1.26% and 0.27% to close at 51,176.96 and 7,722.72, respectively, while the Nasdaq index increased by 0.45% to close at 27,190.86.
European equities ended the week lower, despite a rebound on Friday, as a sharp rise in government bond yields, elevated energy prices and concerns over France’s fiscal outlook weighed on risk appetite. Compared to last week, the German DAX, CAC 40 and FTSE 100 decreased by 0.70%,2.24% and 2.18% to close at 25231.2, 7,897.19 and 10,461.95 respectively.
Asian equities ended the week lower, as surging global bond yields and higher oil prices pressured sentiment, while investors awaited the US September employment report for direction on Federal Reserve policy. Compared to last week, the Hang Seng Index and TOPIX Index decreased by 2.19% and 0.91 to close at 23,972.29 and 4,091 respectively.
Next week, global markets are likely to remain volatile as investors monitor the sustainability of the bond-market recovery, oil-price movements, central-bank commentary and the implications of the weaker US labour-market data for Federal Reserve policy.
DOMESTIC ECONOMY
Nigeria’s Composite PMI Rises to 53.00 in September 2026 Amid Persistent Cost Pressures
Nigeria’s composite PMI rose to 53.00 points in September 2026 from 52.70 in August, marking the fourth consecutive month of expansion in overall economic activity, according to the CBN. The improvement was driven by stronger output, new orders, employment and raw material inventories, with 23 subsectors recording expansion. Industry PMI also strengthened to 52.00 points from 50.60, while Services remained broadly stable at 53.20 points and Agriculture moderated slightly to 53.10 points, extending its expansion streak to 26 months. However, the 0.80-point increase in composite input prices, alongside a 0.50-point decline in output prices, points to continued cost pressures across the economy.
External Reserves Surge Past $54 Billion, Driven by Strong Q1 2026 Capital Inflows
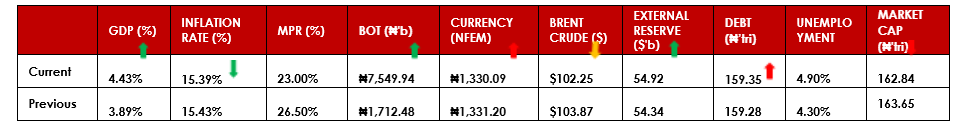
Nigeria’s external reserves rose by $9.29billion in the first nine months of 2026 to $54.86billion as of September 24, representing a 20.40% increase from $45.57billion at the start of the year and more than seven times the $1.32billion increase recorded over the same period in 2025. The reserve position has already exceeded the CBN’s projected 2026 year-end level of $51.04billion, strengthening the country’s external liquidity buffer. The accumulation coincided with an 83.80% year-on-year increase in foreign capital inflows to $10.37billion in Q1 2026, supported significantly by portfolio investment. However, reliance on portfolio inflows exposes reserve accumulation to shifts in interest rates, exchange-rate expectations and global investor sentiment.
Federal Government Seeks $1.5 Billion in Fresh World Bank IDA Credits for Climate and Social Programs
The Federal Government is seeking $1.50billion in fresh World Bank financing through three proposed $500.00million IDA credits targeting climate resilience, early childhood development and social protection. The earliest facility, an additional $500.00million for the Agro-Climatic Resilience in Semi-Arid Landscapes (ACReSAL) project, is scheduled for World Bank board consideration on October 29, 2026, while the other two facilities are expected in March 2027. If approved, the proposed financing would add to Nigeria’s external borrowing pipeline at a time when total public debt stood at ₦166.79trillion as of June 2026, with external debt accounting for $54.52billion.
Nigeria’s External and Public Debt Climb as Borrowing Reaches ₦166.79 Trillion by Mid-2026
Nigeria’s external debt increased by $11.40billion to approximately $54.50billion as of June 2026, from $43.10billion when President Bola Tinubu assumed office, driven by increased borrowing from multilateral lenders, Eurobond issuances and syndicated financing. World Bank exposure rose from $15.40billion to $20.70billion, while Nigeria also raised $2.20billion through a Eurobond in December 2024, $2.35billion in November 2025 and drew $1.50billion from a $5.00billion UAE derivatives financing arrangement in 2026. Overall public debt reached ₦166.79trillion as of June 2026, with domestic debt at ₦91.59trillion and Federal Government external debt at ₦65.77trillion, highlighting the continued expansion of government borrowing.
Next week, attention will remain on naira stability, liquidity and fixed-income market conditions, alongside developments in oil prices, external reserves and government borrowing.
EUROBOND MARKET
Nigerian sovereign Eurobonds ended the week weaker, with the average yield rising to 7.79% from 7.54%, driven by broad-based selling across the curve. Long-dated bonds led the move, with the 2051 yield rising to 8.76% from 8.53%, while the 2046 and 2049 yields increased to 8.64% and 8.61%, respectively. The weakness came amid a global bond sell-off, with the US 10-year Treasury yield reaching 5.34%, its highest level since 2002, as elevated oil prices and inflation concerns increased pressure on global borrowing costs.
Next week, Nigeria’s Eurobonds will likely react to US Treasury yields, US employment data, oil prices and broader emerging-market risk sentiment.
ALTERNATIVE ASSETS
GOLD
Gold fell 3.59% W-o-W to close at $4,133.70/oz, extending its decline for a second consecutive week. The sell-off was driven by a stronger US Dollar and elevated Treasury yields, which reduced the appeal of non-yielding bullion, although weaker-than-expected September payrolls and softer inflation data eased expectations of an October Federal Reserve rate hike and supported a late-week recovery.
OIL
Brent rose 0.11% W-o-W to close at $102.25 per barrel, while WTI fell 1.60% to $91.11 per barrel. Oil prices remained volatile as Middle East supply risks and reports of additional US military deployments supported prices earlier in the week, before expectations of emergency reserve releases and additional fuel availability weighed on the market. The G7’s decision to release 100million barrels of oil and diesel from emergency reserves subsequently reduced some of the supply-risk premium.
ETFs
US-listed ETF activity remained strong, with ETF.com recording $17.50billion of net inflows on September 30, led by broad US equity ETFs including the Vanguard S&P 500 ETF at $4.45billion and Invesco QQQ at $3.13billion, while fixed-income products such as the Vanguard Tax-Exempt Bond ETF and investment-grade corporate bond ETFs also attracted sizeable inflows. Separately, LSEG Lipper data showed global equity funds attracted $34.76billion in the week through September 30, while bond funds received $4.76billion and gold and precious-metals funds gained $275.20million, indicating continued risk appetite despite elevated bond yields.
Next week, Federal Reserve meeting minutes and rate expectations, US Treasury yields and the Dollar, Middle East developments, emergency oil-stock releases and continued ETF flows will remain key drivers of Gold, Oil and broader alternative-asset market sentiment.
MONEY MARKET AND FIXED INCOME
System liquidity was highly volatile during the week, rising 37.01% to ₦8.84trillion from ₦6.45trillion as OMO maturities and other inflows boosted cash availability. The liquidity build-up was followed by a significant CBN sterilisation, as the September 29 OMO auction attracted ₦6.40trillion in subscriptions and resulted in ₦4.69trillion in allotments, compared with ₦2.43trillion of OMO maturities on the same day. The larger-than-expected allotment subsequently reversed much of the liquidity surplus, with system liquidity falling to ₦4.70trillion by October 1.
The volatile liquidity position was reflected in funding rates, although rates remained materially below the previous week following the CBN’s September policy-rate cut. The overnight rate closed at 20.80% on October 2, down from 20.98% the previous week, while the OPR declined to 20.40% from 20.80%. Meanwhile, the Nigerian Overnight Financing Rate (NOFR) remained unchanged at 20.00% while the average secondary-market T-bill yield fell to around 17.84%, compared with 18.30% previously, as investors continued to reprice short-term instruments following the 350bps reduction in the MPR.
Domestic FGN bond yields were mixed during the week, with the market initially facing some selling pressure as liquidity was absorbed, before stabilising toward the end of the period. The average FGN bond yield rose to 15.87% on October 1 from 15.84% in the previous session, although benchmark securities remained broadly anchored around the mid-15% to 16% range. By October 2, yields stood at 15.78% on the Feb-2028 bond, 16.10% on the Apr-2029, 16.25% on the Feb-2031 and 16.22% on the Jun-2038, while the September 23 NTB auction continued to influence pricing, having cleared at 15.50%, 15.80% and 15.89% across the 91-day, 182-day and 364-day tenors, respectively, with ₦4.23trillion in subscriptions against ₦600billion offered.
Next week, money-market conditions are expected to remain volatile as the impact of the CBN’s ₦4.69trillion OMO sterilisation filters through, while T-bill and FGN bond yields could remain under downward pressure if liquidity stabilises and demand for fixed-income assets persists.
DOMESTIC MARKETS
EQUITIES MARKET
The market opened for four trading days this week as the Federal Government declared Thursday October 1, 2026, as a public holiday to mark Independence Day celebration. The NGX All-Share Index and Market Capitalization depreciated by 0.52% and 0.50% to close the week at 250,808.27 and ₦162.843 trillion respectively compared to 252,113.41 and ₦163.65trillion last week
A total turnover of 3.166 billion shares worth ₦155.023 billion in 206,662 deals was traded this week by investors on the floor of the Exchange, in contrast to a total of 4.689 billion shares valued at ₦240.824 billion that exchanged hands last week in 261,198 deals..
On a sectoral basis, major sectors closed negative, with the Banking, Consumer Goods, and Industrial Goods indices decreasing by -1.33%, -0.91%, and -0.26 % while the Oil & Gas and Insurance indices closed positive increasing by 0.05% and 0.61% respectively.
Notable gainers this week were ABC TRANSPORT PLC and CRITICAL MINERALS FINANCING CORP PLC while SOVEREIGN TRUST INSURANCE PLC and E-TRANZACT INTERNATIONAL PLC topped the losers list.
SUPPLEMENTARY LISTINGS
Guinea Insurance Plc: Listing of 3,206,838,021 Ordinary Shares of 50 Kobo Each at ₦1.10 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX) following the Company’s rights issue of 5,295,200,000 ordinary shares at ₦1.10 per share, increasing its issued and fully paid-up share capital from 7,942,800,000 to 11,149,638,021 ordinary shares.
Regency Alliance Insurance Plc: Listing of 3,684,210,525 Ordinary Shares of 50 Kobo Each at ₦0.95 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX) following the Company’s private placement of 7,368,421,052 ordinary shares at ₦0.95 per share, increasing its issued and fully paid-up share capital from 18,679,385,062 to 22,363,595,587 ordinary shares.
The Initiates Plc: Listing of 1,110,018,448 Ordinary Shares of 50 Kobo Each at ₦7.00 and ₦9.50 Per Share.
Listed on the Daily Official List of Nigerian Exchange Limited (NGX), comprising 177,996,310 ordinary shares issued through a rights issue at ₦7.00 per share and 932,022,138 shares through a public offer at ₦9.50 per share, increasing its issued and fully paid-up share capital from 889,981,552 to 2,000,000,000 ordinary shares.
Next week, the NGX is expected to remain sensitive to profit-taking and sector rotation following the recent pullback, while investor attention will remain on corporate disclosures, banking-sector earnings expectations and developments around ongoing capital-market activities.
| Currency Pair | Exchange Rate | Change |
| GBP/NGN | ₦1,761.91 | -1.23% |
| EUR/NGN | ₦1,497.44 | -5.57% |
| CAD/NGN | ₦933.85 | -5.21% |
CURRENCY
| (₦/$) | 02/10/2026 | 28/09/2026 | W-O-W% |
| NAFEM | 1,330.09 | 1,331.32 | 0.09% |
| Parallel | 1,375.00 | 1,390.00 | 1.08% |
TOP GAINERS
| Ticker | Open | Close | Gain | % |
| ABC TRANSPORT | 5.1 | 7.4 | 2.3 | 45.10% |
| CMFC | 3.26 | 4.49 | 1.23 | 37.73% |
| LIVINGTRUST | 2.6 | 3.45 | 0.85 | 32.69% |
| VFD GROUP PLC | 11.4 | 13.5 | 2.1 | 18.42% |
| CWG PLC | 18 | 20.75 | 2.75 | 15.28% |
TOP LOSERS
| Ticker | Open | Close | Loss | % |
| SOVEREIGN TRUST | 2.4 | 2.1 | -0.3 | -12.50% |
| E-TRANZACT | 12.5 | 11 | -1.5 | -12.00% |
| LEARN AFRICA | 8.6 | 7.65 | -0.95 | -11.05% |
| PZ CUSSONS | 73.8 | 66.4 | -7.4 | -10.03% |
| FTGINS | 2 | 1.81 | -0.19 | -9.50% |
DISCLAIMER
This publication is produced by Alpha10 Group solely for the information of users who are expected to make their own investment decisions without undue reliance on any information or opinions contained herein. The opinions contained in the report should not be interpreted as an offer to sell or a solicitation of any offer to buy any investment. Alpha10 Group may invest substantially in securities of companies using information contained herein and may also perform or seek to perform investment services for companies mentioned herein. Whilst utmost care has been taken in preparing this document, no responsibility or liability is accepted by any member of the Group for actions taken as a result of information provided in this publication.
Alpha10 Group. 13, Mambolo Street, Zone 2, Wuse, Abuja. Visit us at www.alpha10group.com.